

The founder discount
PERFORMANCE THIS WEEK
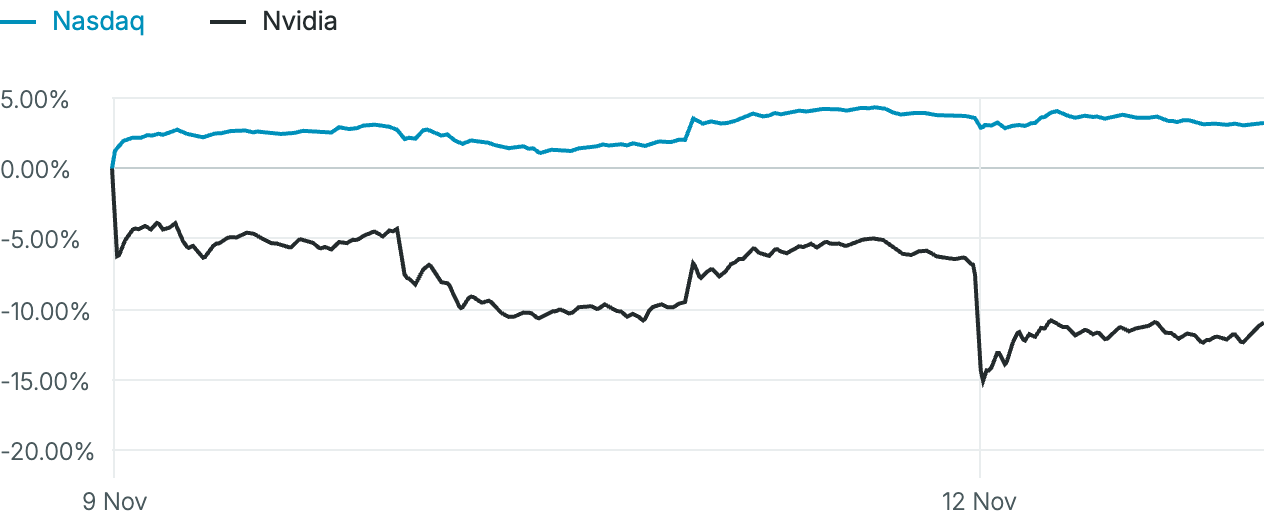
Source: FactSet As of November 12, 4 PM ET
Nvidia, ex-Jensen
Nvidia’s management transition represents a meaningful but measured setback, with potentially greater implications for valuation than near-term earnings. Jensen Huang’s departure leaves CFO Colette Kress serving as interim CEO while retaining her finance responsibilities, alongside Harvey C. Jones as the newly appointed board chair.
The company retains substantial management depth across engineering, software, operations and finance. However, replacing Huang’s strategic vision, influence and ability to coordinate large-scale investments across the AI ecosystem will be challenging. Existing commitments should remain intact, although negotiating new partnerships could become more difficult. His absence may also constrain organisational agility, even as development of Rubin Ultra and Feynman is already well advanced.
A 12–24-month order backlog and a clearly defined product roadmap extending two to three years provide important support for earnings over the next 12–18 months. Consequently, the more immediate impact may emerge through valuation compression as investors reassess leadership continuity and Nvidia’s role in financing AI infrastructure expansion.
Apple’s transition beyond Steve Jobs offers an imperfect but relevant precedent. Uncertainty surrounding a visionary leader’s departure can weigh on valuation until sustained execution restores confidence. Nvidia’s investment case rests on its ability to preserve technological leadership and convert existing demand into earnings. FactSet consensus projects growth of 70.6% in earnings for 2027, which can provide fundamental support to the company’s shares.
Equities
Wall Street had long viewed Nvidia’s Jensen Huang as the central figure in the artificial intelligence boom. His reported departure now raises questions about the durability of a rally closely associated with his leadership.
Huang’s reported resignation on Thursday threatens to unsettle the AI expansion he helped drive. It also highlights the risks of attributing a company’s success so heavily to a single individual. Nvidia shares fell as much as 14.08% before recovering some ground to close 4.34% lower.
His departure would leave a significant leadership void at the heart of the AI industry. The leadership turmoil has erased hundreds of billions of dollars from Nvidia’s market capitalisation, with repercussions extending across global financial markets.
- S&P 500 7,592.40 -0.35%
- Nasdaq Composite 25,366.09 -0.39%
- Dow Jones Industrial 52,297.09 -0.36%
- DAX 26,771.88 +0.41%
- CAC 40 8,361.36 +0.34%
- FTSE 100 10,863.09 +0.25%
Currencies
The US dollar strengthened against major currencies on Thursday, reaching a 19-month high as Treasury yields moved higher.
The euro fell to its weakest level against the dollar since April 2025, while the dollar index remained at its highest level since that month. The Japanese yen weakened to its lowest level against the dollar since September.
- DXY 103.18 +0.26%
- EUR/USD $1.1054 -0.29%
- GBP/USD $1.3235 -0.34%
- USD/JPY ¥159.84 +0.04%
- Bitcoin $71,496.01 -3.79%
- Ethereum $2,016.61 -2.50%
Fixed Income
US Treasury yields rose across maturities on Thursday. The two-year yield reached its highest level since 14 October, while the 10-year yield climbed to its highest since 21 October.
The US government opened fiscal year 2027 with an October budget deficit of $404 billion, a record for the month, according to Treasury Department data released on Thursday. The shortfall widened by $120 billion, or 42%, from a year earlier as receipts declined and spending increased sharply.
Demand was subdued at the Treasury’s $25 billion auction of 30-year bonds, the final offering in this week’s $125 billion of coupon-bearing debt issuance. The auction cleared at a high yield of 5.441%, 0.5 bps above the pre-auction trading level. The bid-to-cover ratio stood at 2.36x, its lowest since June.
Euro area government bond yields rose on Thursday. Germany’s 10-year Bund yield was on course for a weekly increase following four consecutive weeks of declines.
Money markets assigned an approximately 80% probability to a 25 bps ECB rate increase in December and fully priced in two such increases by mid-2027.
Italy sold €7.25 billion of medium- and long-term bonds to solid demand. The country’s 10-year BTP yield rose 1.1 bps.
- US Treasury 10-year +14.4 bps 5.134%
- German Bund 10-year +2.6 bps 3.358%
- UK Gilt 10-year +7.3 bps 5.302%
- France OAT 10-year +4.0 bps 4.836%
- Italy 10-year +1.1 bps 4.343%
Commodities
Gold prices fell for a third consecutive session on Thursday, reaching their lowest level in more than a year.
Crude benchmarks advanced as escalating tensions in the Middle East outweighed the Department of Energy’s report of inventory builds across both crude oil and refined products. WTI and Brent reversed earlier losses in morning trading after the US President said, “We don't need a deal with Iran. Those days have long since passed.”
Attacks on tankers in and around the Strait of Hormuz continued overnight. Yemen’s Houthis also claimed to have targeted a pumping station on Aramco’s East-West pipeline and an oil facility in Yanbu. Separately, Ukraine’s military said it had struck five major Russian oil refineries since 30 October, including the country’s largest refinery in Omsk, where an attack on Wednesday reportedly lasted eight hours.
- Spot Gold $3,875.01/oz -2.82%
- Spot Silver $50.00/oz -3.22%
- WTI crude $88.68 +2.62%
- Brent Crude $95.76 +3.39%
Key data to move markets today
Attention today turns to PPI and Fedspeak.
 French CPI, Eurozone GDP, Employment Change and Trade Balance, and speeches by De Nederlandsche Bank President Olaf Sleijpen, ECB Executive Board members Frank Elderson and Isabel Schnabel
 GDP, Industrial and Manufacturing Production
 PPI, Core PPI and speeches by Fec Vice Chair Philip Jefferson, Fed Governor Michelle Bowman and San Francisco Fed President Mary Daly
FEATURED TODAY
Earnings Scoreboard: Burn rate, beat rate
Earnings are still beating expectations each week, but the multiple investors will pay for them is falling.
The season is winding down and each company reporting this week tests a distinct source of pricing power.
Read EXANTE’s Earnings Scoreboard by Multi-Asset Strategist Horacio Coutino for the full picture.
Renée Friedman, PhD
Editor-in-Chief, EXANTE
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
This article is provided to you for informational purposes only and should not be regarded as an offer or solicitation of an offer to buy or sell any investments or related services that may be referenced here. Trading financial instruments involves significant risk of loss and may not be suitable for all investors. Past performance is not a reliable indicator of future performance. Sentiments are generated automatically and are not investment advice.
 Back to all insights




Created by professionals. For professionals.
