

Less legislation, no less uncertainty
Chart of the Day
Different Congress, familiar risk premia
With congressional control still unconfirmed at the time of writing, the relevant base case is Democratic gains producing divided government, not a wholesale policy reversal. For US assets, that favours selective repricing over a durable election trade.
Equities could benefit as electoral uncertainty clears, but Washington cannot legislate better returns on AI capital. Presidential veto power limits sweeping federal restrictions; state-level data-centre approvals remain the sharper political risk for technology and infrastructure exposures.
Treasuries deserve less enthusiasm than the gridlock playbook suggests. Major fiscal shifts look improbable over the next two years, although a Democratic scenario could lift spending slightly. Deals to restore social spending and keep defence outlays could sustain deficits, limiting any compression in long-end term premia. The 2027 debt ceiling adds a separate source of funding-market volatility.
Nor would a Democratic advance deliver tariff disarmament. Selective concessions could be outweighed by renewed executive action, leaving import-sensitive margins exposed. The dollar, meanwhile, remains a rates trade, not a political one. The market’s mistake would be to price legislative paralysis as macroeconomic tranquility.
Equities
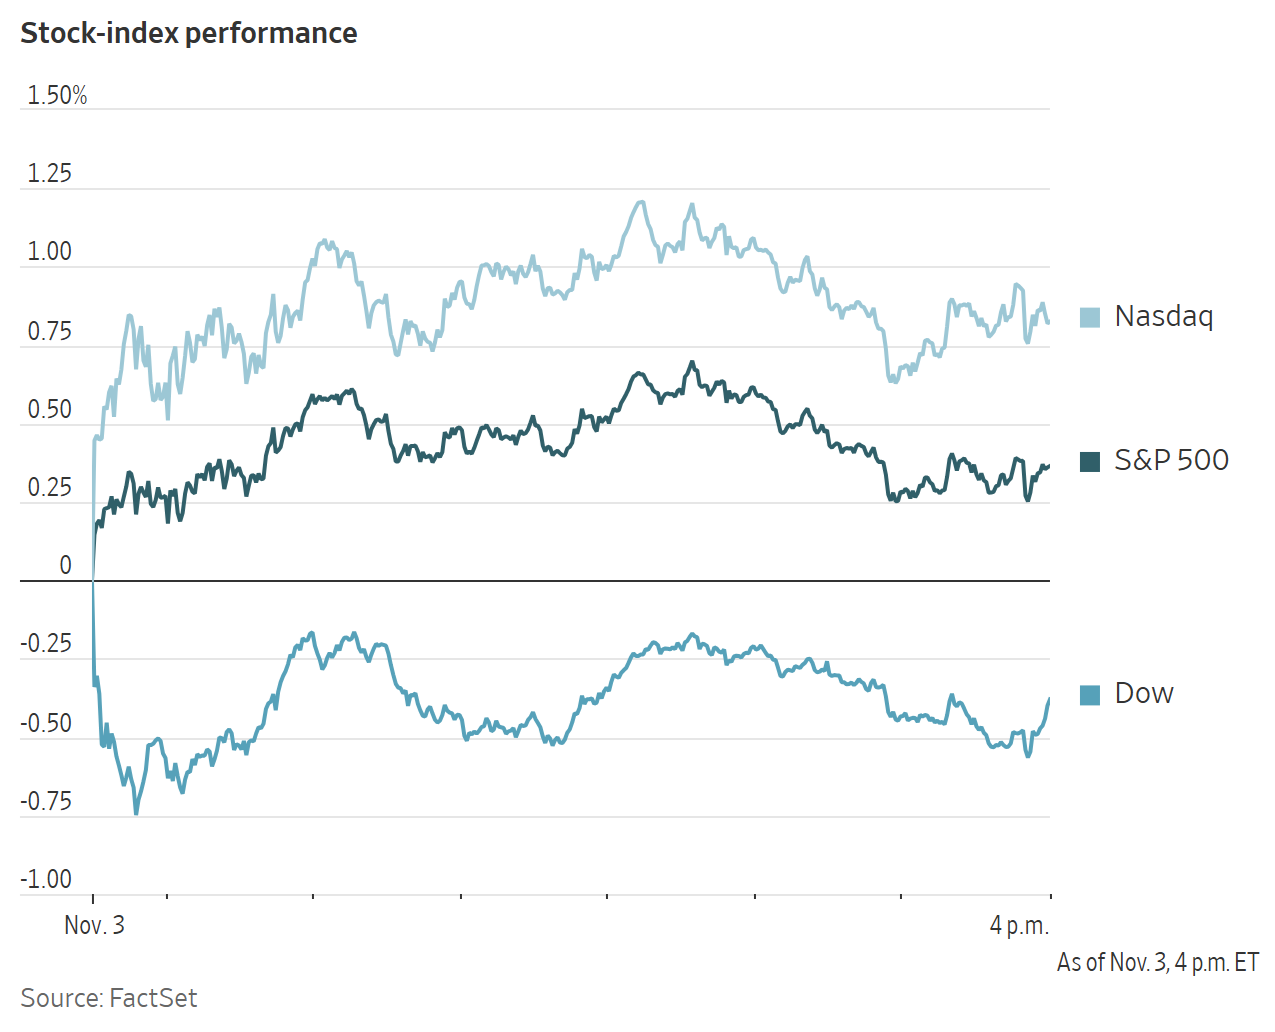
Tech stocks ended a three-session decline as investors shifted their focus from earnings to the US midterm elections. Gains in semiconductors helped lift equities, with Nvidia and Broadcom partly offsetting Apple’s decline, which weighed on the Dow industrials. Apple fell after Monday’s Q3 results indicated that a global memory-chip shortage could slow growth.
At the US equity market close, prediction markets favoured Democratic control of the US Senate.
- S&P 500 7,568.92 +0.36%
- Nasdaq Composite 25,372.01 +0.83%
- Dow Jones Industrial 51,786.72 -0.38%
- DAX 25,864.62 -0.45%
- CAC 40 8,020.31 -0.34%
- FTSE 100 10,638.43 -1.14%
Currencies
The dollar fluctuated between modest gains and losses on Tuesday. After declining as much as 0.17%, it turned higher following the Labor Department’s Job Openings and Labor Turnover Survey (JOLTS), which showed job openings, a gauge of labour demand, rising by 333,000 to 7.523 million, above the 7.100 million consensus forecast.
Central banks in Britain, Norway and Sweden are scheduled to announce policy decisions this week.
- DXY 101.86 +0.06%
- EUR/USD $1.1193 +0.07%
- GBP/USD $1.3411 +0.04%
- USD/JPY ¥158.69 +0.47%
- Bitcoin $77,840.35 +1.45%
- Ethereum $2,292.72 +1.67%
Fixed Income
Longer-dated US Treasury yields rose on Tuesday as investors awaited US midterm election results. Eurozone yields also rose. Euro short-term rate forwards, or ESTR forwards, implied a deposit rate of 2.73% by December 2026 and 3.17% by late 2027, up from the current 2.50%.
- US Treasury 10-year +6.5 bps 4.974%
- German Bund 10-year +4.0 bps 3.350%
- UK Gilt 10-year +7.2 bps 5.269%
- France OAT 10-year +3.6 bps 4.938%
- Italy 10-year +1.9 bps 4.428%
Commodities
Gold reversed earlier gains to finish slightly lower on Tuesday as a stronger dollar and higher Treasury yields weighed on prices. WTI and Brent closed at their lowest levels in nearly a month as markets tracked developments in US - Iran peace talks. Both benchmarks initially rose on reports of US strikes on several targets on Qeshm Island, the Iranian foreign minister’s rejection of the US approach to talks, and a Reuters report citing senior Iranian officials who said the two sides remained far from a deal.
- Spot Gold $3,930.48/oz -0.41%
- Spot Silver $49.79/oz -1.70%
- WTI crude $96.76 +0.52%
- Brent $104.38 +0.16%
Corporate Earnings Today
Companies reporting on Wednesday, 4th November:
Key data to move markets today
Attention turns to the implications of the US midterm election results and BoJ’s monetary policy meeting minutes.
 Eurozone, Spanish, Italian, French and German HCOB Composite and Services PMIs, Eurozone Harmonised Index of Consumer Prices and Core Harmonised Index of Consumer Prices, and a speech by ECB Chief Economist Philip Lane
 S&P Global Composite and Services PMIs
 ADP Employment Change, S&P Global Composite and Services PMIs, S&P Global Composite and Services PMIs, and ISM Services PMI, ISM Services Prices Paid, ISM New Orders and ISM Employment Indices
 BoJ Monetary Policy Meeting Minutes
FEATURED TODAY
Earnings Scoreboard: Cash conversion at the tollbooth
The connective tissue across last week's and this week's earnings dockets is the repricing of balance-sheet velocity. Find out what to look for in this week’s earnings reports and how the results may move markets.
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
Este artículo se presenta a modo informativo únicamente y no debe ser considerado una oferta ni solicitud de oferta para comprar ni vender inversión alguna ni los servicios relaciones a los que se pueda haber hecho referencia aquí. Operar con instrumentos financieros implica un riesgo significativo de pérdida y puede no ser adecuado para todos los inversores. Los resultados pasados no garantizan rendimientos futuros.
 Volver a todas las perspectivas


Regístrese para recibir perspectivas de los mercados
Regístrese
para recibir perspectivas
de los mercados
Suscríbase ahora Suscríbase ahora

Creado por profesionales. Para profesionales.
