

A blockbuster, not a blessing
INDEX PERFORMANCE
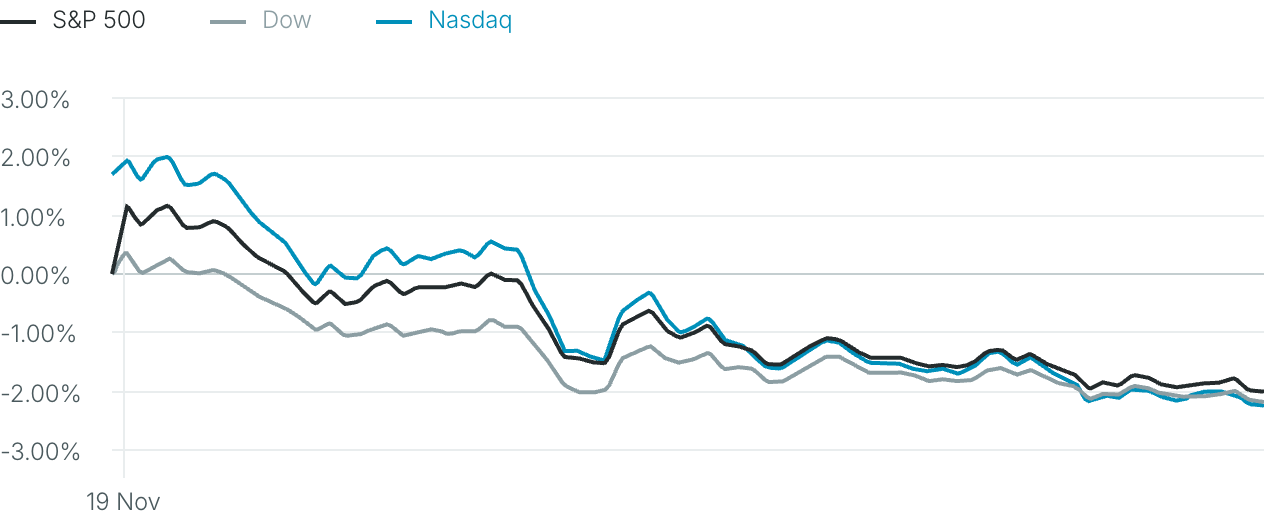
Source: FactSet
Capital has its favourites
Anthropic’s blockbuster flotation suggests investors have not abandoned AI, but have become more discriminating about where to own it. Shares initially climbed about 40% from the $83 offer price, briefly taking the valuation above $2 tn, before retreating towards $95 in afternoon trading. That reversal offers a useful distinction between scarcity at allocation and conviction at prevailing prices.
For investors, the challenge is not how much capital is available, but where it goes. Tight institutional allocations could encourage secondary market buying, potentially funded by trimming established technology holdings. The resulting rotation would flatter the newcomer without necessarily expanding the support to the broader AI trade.
Nor should demand for a leading frontier laboratory be mistaken for blanket endorsement of its supply chain. Indebted cloud operators and less differentiated infrastructure providers still face scrutiny over financing costs, utilisation and returns. Elevated volatility adds another constraint to positions sensitive to interest rates and risk appetite. Anthropic’s reception therefore signals an open financing window for exceptional issuers, not immunity from the competitive pressures, pricing uncertainty and issuance demands confronting the sector.
Equities
All three major indices dropped on Thursday. One reason may be that big IPOs prompt investors to sell other holdings to make room for the new position.
Anthropic was that new position yesterday. The AI giant opened at $111.50. This was 33.92% above its $83 offer price, in the biggest IPO in history. It then pared gains to close at $97.17, up 17.07%.
- S&P 500 7,175.83 -2.02%
- Nasdaq Composite 23,879.20 -2.25%
- Dow Jones Industrial 49,097.06 -2.19%
- DAX 25,463.81 -1.06%
- CAC 40 8,080.74 -0.81%
- FTSE 100 10,452.68 -0.93%
Currencies
The dollar rallied again on Thursday, driven by hawkish Federal Reserve signals on inflation and safe-haven demand. The rally started on 10 November when hotter-than-expected US inflation data raised Fed tightening expectations. The dollar index reached its highest level since “Liberation day” on 2 April 2025.
Sterling retreated from a 20-month high against the euro and fell against the dollar on Thursday due to the surge in US dollar demand alongside a drop in expectations of an immediate BoE interest rate hike.
- DXY 103.94 +0.15%
- EUR/USD $1.0966 -0.06%
- GBP/USD $1.3086 -0.47%
- USD/JPY ¥159.67 +0.22%
- Bitcoin $61,502.60 -1.24%
- Ethereum $1,739.97 -1.27%
Fixed Income
US Treasury yields edged lower on Thursday. According to the CME Group's FedWatch Tool, fed funds futures on Thursday priced in a 96.4% chance of a 25 bps hike at the FOMC's December meeting.
The 10-year TIPS auction drew solid demand on Thursday, but the 10-year TIPS yield extended its decline afterward.
Eurozone bond yields were higher on Thursday due to hawkish Fed signals, heavy sovereign debt issuance and inflation concerns.
- US Treasury 10-year -3.2 bps 5.048%
- German Bund 10-year +3.6 bps 3.420%
- UK Gilt 10-year +2.8 bps 5.317%
- France OAT 10-year +6.8 bps 4.940%
- Italy 10-year +3.9 bps 4.477%
Commodities
Gold hit a 14-month low on Thursday, pressured by a stronger dollar and Fed rate rise expectations.
Oil settled higher as reports of tanker disruptions in the Strait of Hormuz outweighed rising US crude inventories and forecasts of a global surplus. The WTI December contract expires today; January closed at $82.44.
Iran-backed Houthis also fired missiles at Riyadh. Saudi civil defence said the strike damaged several floors of the city's tallest skyscraper, home to the sovereign wealth fund's headquarters, and nearby buildings, according to state news agency SPA.
The UKMTO said another tanker was struck late yesterday while transiting the SoH, 6 nautical miles north of Khasab, Oman.
Supply-glut concerns were reinforced by the Joint Organizations Data Initiative, which reported that Saudi crude exports jumped nearly 21% in September from August to 5.38 million bpd, the highest since February.
- Spot Gold $3,625.06/oz -2.66%
- Spot Silver $42.85/oz -4.85%
- WTI crude $83.89/barrel +1.22%
- Brent Crude $92.69/barrel +1.39%
Key data to move markets today
Attention will turn to today’s Fedspeak for further indications of the pace of rate rises this year and next.
 German PPI, Eurozone Consumer Confidence and speeches by ECB President Christine Lagarde and Bundersbank President Joachim Nagel
 Public Sector Net Borrowing, Retail Sales and Retail Sales ex-Fuel
 Michigan Consumer Sentiment and Expectations Indices, UoM 1- and 5-year Inflation Expectations and speeches by Fed Governors Christopher Wallace and Lisa Cook
FEATURED TODAY
Alpha Vibes: When scarcity becomes opportunity
How many investable layers does the AI buildout really have?
The media usually talks about five. EXANTE’s own research identifies that there are actually seven, in a unique framework you won’t find anywhere else.
Across all seven, forward earnings estimates rose while share prices fell during the Q3 earnings season. Going into year-end, find out which falling share prices signal opportunity and which signal risk.
Get this exclusive view in EXANTE’s latest Alpha Vibes, by Global Head of Research Renée Friedman and Multi-Asset Strategist Horacio Coutino.
Renée Friedman, PhD
Editor-in-Chief, EXANTE
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
本文提供给您仅供信息参考之用,不应被视为认购或销售此处提及任何投资或相关服务的优惠招揽或游说。金融工具交易存在重大亏损风险,未必适合所有投资者。过往表现并非未来业绩的可靠指标。市场情绪为自动生成,不构成投资建议。
 返回到所有洞察




由专业人士创建。 为专业人士。
