

The US labour market surprises to the upside
STOCK-INDEX PERFORMANCE THIS WEEK
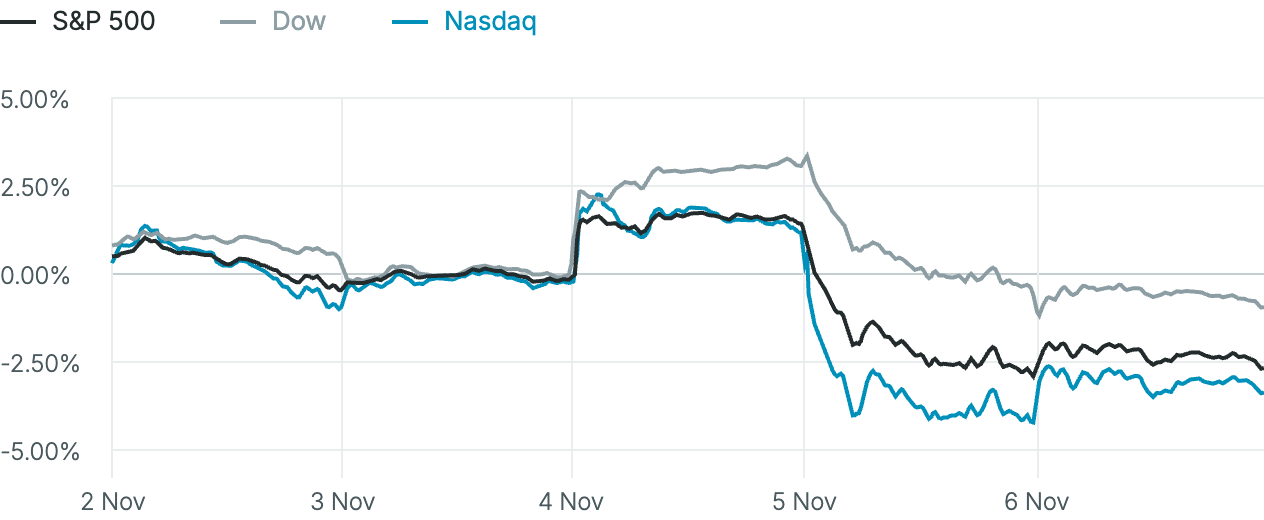
Source: FactSet As of Nov. 6, 4 p.m. ET
The US labour market surges ahead
US job growth surpassed expectations in October. According to the US Bureau for Labor Statistics, nonfarm payroll growth increased 165,000 after an upward revision to the prior two months of 84,000 jobs. The growth was broad-based and was led by business and professional services. This unexpectedly large growth rate is largely attributed to resilient consumer spending and still high rates of business investment. The unemployment rate declined to 4.1% from 4.2% in September despite 421,000 people entering the labour force. Annual wage growth came in at 3.1%.
This news followed last week’s solid JOLTS report, which, combined with historically low layoffs, suggests labour market tightening. However, Fed officials have maintained that the labour market poses no inflation risk. With the PCE index, the Fed's preferred measure at 3.6% in September, and core CPE at 3.1% against a 2% target, the Fed will feel the weight of expectations for a rate hike in December and likely into early next year.
Equities
On Friday markets recovered some of last Thursday’s losses. Technology stocks bounced back, with the semiconductor index rising 4.2%. Nvidia was up 2.8%, Advanced Micro Devices soared 11%, Sandisk rose almost 4%, Tesla climbed 4.2% and SpaceX jumped up 8.6%. Lower oil prices led to a drop in the S&P 500 energy index. It was down 12% for the week, its worst performance since April 2025.
However, all the major indices ended last week down. The Dow Jones Industrials was -0.9%, the Nasdaq fell -3.4% and the S&P 500 was -2.7%, its largest weekly loss since April 2025.
- S&P 500 7,376.86 +0.32%
- Nasdaq Composite 27,579.43 +1.09%
- Dow Jones Industrial 51,285.73 -0.46%
- DAX 25,820.36 -1.92%
- CAC 40 8,139 -0.81%
- FTSE 100 10,673.94 -1.01%
Currencies
The dollar index had its biggest daily percentage gain in nearly five months on Friday. This was due to stronger-than-expected US payrolls report increasing expectations of Fed rate hike in December.
The Japanese yen weakened as Prime Minister Sanae Takaichi unveiled a plan to tap proceeds from the BoJ’s sales of exchange-traded funds to finance investment projects. Bank of Japan Governor Kazuo Ueda said the central bank expects underlying inflation to stay around its 2% target, but recognises there are "some upside risks."
Bitcoin hit an 11-week low due to over $1 billion in crypto liquidations and uncertainty around cryptocurrency regulation following the US midterm election.
- DXY 102.28 +0.72%
- EUR/USD $1.1142 -0.68%
- GBP/USD $1.3355 -0.71%
- USD/JPY ¥158.430 +0.47%
- Bitcoin $7,583.02 -5.99%
- Ethereum $2,238.67 +0.52%
Fixed Income
US Treasury yields rose due to October’s stronger-than-expected nonfarm payroll data and drop in unemployment. The yield curve flattened with the spread between the 2 and 10-year narrowing to 33.5 bps, down from the previous session’s 37.1 bps. According to CME FedWatch, there was a 78% probability of a 25 bps rate hike in December, up from Thursday’s 66.9% chance.
The Eurozone benchmark, the German 10-year bond yield, fell as traders reduced their bets on the extent of ECB rate hikes due to the possible slowdown in global growth after Thursday’s AI sell-off.
- US Treasury 10-year +2.3 bps 4.861%
- German Bund 10-year -1.3 bps 3.263%
- UK Gilt 10-year -2.3 bps 5.150%
- France OAT 10-year +3.4 bps 4.767%
- Italy 10-year +4.4 bps 4.307%
Commodities
Gold prices were down on Friday, weighed down by a stronger US dollar and rising Treasury yields. However, Spot gold was up 5.2% for the week, its best week since August.
Crude oil edged slightly up on Friday. The Brent futures for January fell 17% last week, its steepest weekly percentage drop since the beginning of the COVID pandemic. WTI fell 13% last week.
- Spot Gold $4,069.63/oz -0.43%
- Spot Silver $51.91/oz +0.26%
- WTI crude $90.83/barrel +0.34%
- Brent Crude $98.32/barrel +0.03%
Corporate Earnings Today
Companies reporting on Monday, 9th November:
Key data to move markets today
Markets will be looking to speeches by US Fed officials for further indications of future rate policy.
 German Trade Balance, Eurogroup Meeting and Eurozone Sentix Investor Confidence
 A speech by BoE Governor Andrew Bailey
 Speeches by Fed Vice Chair for Supervision Michelle Bowman, Chicago Fed President Austan Goolsbee and Richmond Fed President Thomas Barkin
 PPI and CPI
 Current Account
FEATURED TODAY
Equity Monthly Review
When the biggest stocks stop leading, where does the market’s strength come from?
In October, the S&P 500 fell 0.93%, but its equal-weight version rose 4.90%, outpacing it by 583 basis points.
Read EXANTE’s Equity Monthly Review by Multi-Asset Strategist Horacio Coutino for the full picture.
Renée Friedman, PhD
Editor-in-Chief, EXANTE
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
本文提供给您仅供信息参考之用,不应被视为认购或销售此处提及任何投资或相关服务的优惠招揽或游说。金融工具交易存在重大亏损风险,未必适合所有投资者。过往表现并非未来业绩的可靠指标。
 返回到所有洞察




由专业人士创建。 为专业人士。
