
Are households ahead of the curve?

 S&P 500 +0.28% to 7,712.57 US 10-year yield -2.6 basis points to 5.115% Spot gold +0.06% to $4,122.53 an ounce DXY -0.25% to 101.71
What to look out for today
Companies reporting on Wednesday, 21st October: Meta Platforms, Tesla, Abbott Laboratories, AT&T, CME Group, Thermo Fisher Scientific, IBM, Lam Research Group, QuantumScape, NextEra Energy, Crown Castle, Northern Trust, Teledyne, Las Vegas Sands, Packaging Corporation of America, Southwest Airlines
Key data to move markets today
EU: German Bundesbank “Buba” Monthly Report and speeches by ECB Chief Economist Philip Lane, German Bundersbank President Joachim Nagel, ECB Executive Board member Piero Cipollone and ECB President Christine Lagarde
UK: CPI, PPI and RPI
JAPAN: Adjusted Merchandise Trade Credit, Exports, Imports and Merchandise Trade Balance Total
Global Macro Updates
Housing’s higher-for-longer cautionary tale. US households are sounding a clearer cautionary signal, although their spending has remained more resilient than their mood. The October LSEG/Ipsos consumer sentiment index, published on 16 October, fell 5.3 points to 45.2, its weakest since 2011. The University of Michigan’s preliminary October reading also slipped to 46.3, with durable-goods buying conditions deteriorating amid high prices and borrowing costs, which is an obviously uncomfortable backdrop for discretionary demand.
Housing gives that pessimism a harder statistical edge. September pending home sales fell 7.3% to a record-low index reading of 66.0, with every region declining. Housing starts dropped 5.2% to a 1.221mn annualised pace, while October builder confidence reached its lowest since June 2012. Aggregate permits looked steadier, falling just 0.2%, but single-family authorisations declined 4%, hardly a reassuring pipeline for residential investment.
The transmission mechanism is straightforward, if uneven. Freddie Mac’s average 30-year mortgage rate stood at 7.40% on 15 October, penalising new buyers while encouraging existing borrowers to retain cheaper loans rather than move. That lock-in constrains turnover and mobility; higher construction financing and material costs compound the pressure on builders.
Yet the opposing evidence deserves more than a footnote. Q2 GDP grew at a 2.2% annualised rate, against 2.5% in the first quarter, supported by consumption, investment and exports. September’s ISM manufacturing and services PMIs remained expansionary at 54.5 and 54.9, respectively. Crucially, 13 services industries reported growth, up from 12 in August. This suggests modestly broader participation rather than an expansion confined to technology, even as construction contracted. Broader output growth, however, does not imply stronger hiring. The services employment index barely exceeded the stagnation threshold at 50.1.
And yet, softer housing has not delivered benign inflation. September PPI rose 1.3% monthly and 6.3% annually; sell-side analysts have highlighted diesel’s transmission into freight and production costs. This, therefore, is cost pressure, not proof of stronger real demand. Contrary to perma-bears’ thinking, the risk is not an imminent, synchronised recession. The risk is an uneven slowdown, with persistent inflation keeping yields restrictive until broader activity weakens.
US Stock Indices
Dow Jones Industrial Average +1.02%
Nasdaq 100 -0.132%
S&P 500 +0.28%, with 9 of the 11 sectors of the S&P 500 up
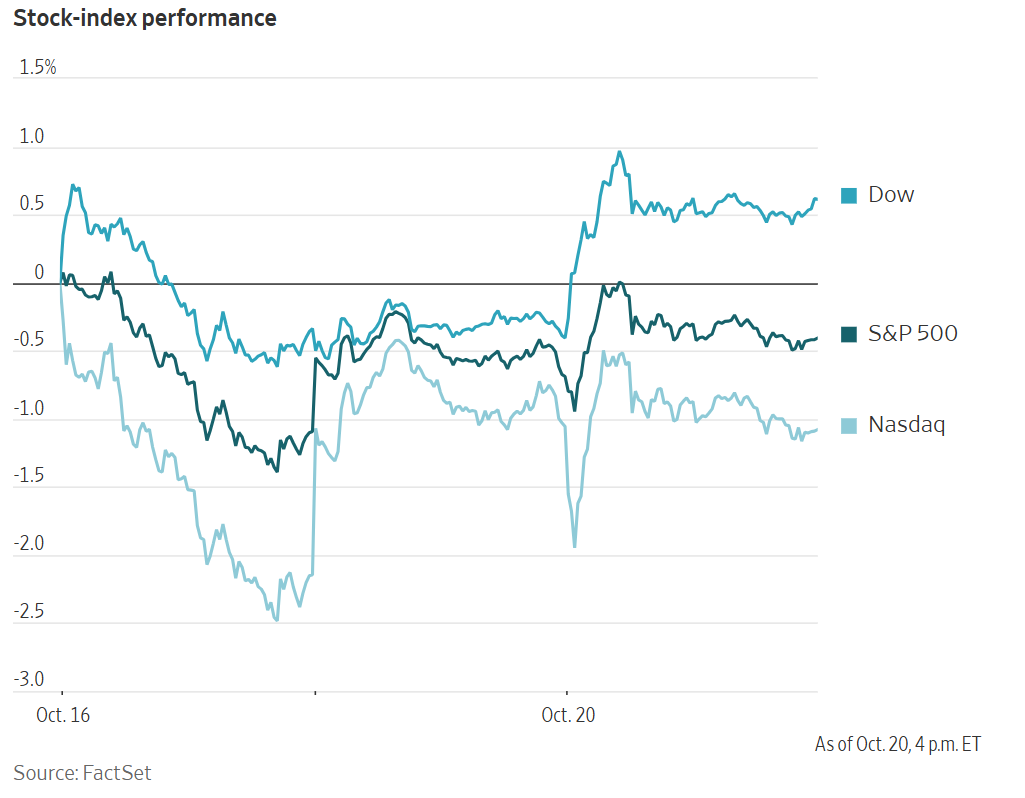
US equity indices were mixed on Tuesday as investors focussed on value stocks such as healthcare, while technology lagged after rebounding on Monday. However, more than 400 firms in the S&P 500 rose.
The Dow Jones Industrial Average rose 529.85 points, or +1.02%, to 52,495.88, the S&P 500 gained 21.84 points, or +0.28%, to 7,712.57 and the Nasdaq Composite lost 6.07 points, or -0.02%, to 26,424.82.
In corporate news, United Airlines forecast weaker-earnings for the final three months of the year. This forecast highlighted how surging jet fuel prices are affecting airline profits despite resilient demand for air travel.
Boeing won US regulator approval for its 737 Max 10 jet, capping off a lengthy certification saga that was disrupted by two fatal crashes.
Netflix saw its shares fall more than 5% to $68.69 in after-hours trading on Tuesday after issuing a weaker-than-expected forecast for fourth-quarter profits.
Corporate Earnings Reports
Posted on Tuesday, 20 October from The Pulse, our real-time AI-driven news tool. Available exclusively on the EXANTE Web Platform
Equifax reported its Q3 2026, posting revenue of $1.69bn vs $1.69bn expected, up +10% y/y, and adjusted EPS of $2.26 vs $2.20 expected, up +11% y/y. Key drivers included US mortgage revenue increasing +15% y/y, Workforce Solutions revenue rising +7% y/y to $693.9mn, and US Information Solutions advancing +13% y/y to $599.1mn. For FY26, Equifax lowered revenue guidance to $6.65bn-$6.68bn vs $6.73bn expected, with adjusted EPS projected at $8.45-$8.55 vs $8.50 expected. In corporate deals, the Círculo de Crédito acquisition remains on track to close in Q4 2026. The chief executive stated that the firm delivered a strong third quarter despite a weaker mortgage market driven by increasing interest rates.
GE Aerospace reported Q3 2026 adjusted revenue of $13.29bn vs $12.87bn expected, up +18% y/y, and adjusted EPS of $2.25 vs $2.01 expected, up +36% y/y. Total orders rose +49% y/y to $19.0bn, driven by Commercial Engines revenue expanding +21% y/y to $10.34bn. For full-year 2026, management upgraded adjusted EPS guidance to between $8.00 and $8.10 vs $7.92 expected, with adjusted revenue growth projected at +19% to +20% and free cash flow between $9.1bn and $9.4bn. Operationally, the company entered an agreement to acquire CPP to expand aerospace castings capacity. The chief executive stated that strong demand drove order momentum and prompted guidance increases across all metrics.
General Motors reported Q3 2026 revenue of $50.02bn, up +2.9% y/y vs $48.7bn expected, and adjusted EPS of $3.70, up +32.2% y/y vs $3.63 expected. Adjusted EBIT rose +21.6% y/y to $4.11bn vs $4.24bn expected, with North America adjusted EBIT up +43.4% y/y to $3.59bn and International Operations falling -87.7% y/y to $28mn. For the full year, the company refined adjusted EPS guidance to $12.75 to $13.75 and raised adjusted automotive free cash flow guidance to $11.5bn to $12.5bn. The group also authorised a new $20bn share buyback programme following the completion of its $6bn repurchase plan. The chief executive noted that the company was performing well and actively working to maintain momentum despite inflationary pressures.
Halliburton reported Q3 2026 revenue of $5.70bn vs $5.58bn expected and adjusted EPS of $0.60 vs $0.58 expected. Adjusted operating income reached $731mn vs $730mn expected. By division, Completion and Production generated $3.09bn, whilst Drilling and Evaluation delivered $2.61bn. Regionally, North America contributed $2.16bn, followed by Middle East and Asia at $1.41bn, Latin America at $1.12bn, and Europe, Africa and CIS at $1.02bn. Operationally, the company secured an integrated deepwater contract from Eni offshore Cyprus and an appraisal campaign contract from bp offshore Brazil. Halliburton's chief executive stated that efforts to restore production, rebuild inventories, and strengthen energy security would drive multi-year demand growth for oilfield services.
Hasbro reported its Q3 2026 financial results, delivering revenue of $1.60bn vs $1.48bn expected, up +15% y/y. Adjusted EPS was $2.90 vs $1.86 expected, whilst adjusted EBITDA reached $604.5mn vs $442mn expected. Growth was led by Wizards and Digital Gaming revenue rising +31% y/y to $747.2mn, propelled by Magic: The Gathering revenue jumping +34% y/y to $616.1mn. Consumer Products revenue increased +4% y/y to $827.9mn, and Entertainment revenue grew +9% y/y to $20.2mn. For FY26, the company raised adjusted EBITDA guidance to between $1.58bn and $1.63bn vs $1.47bn expected, alongside constant-currency revenue growth of +7% to +9%. Leadership stated that an expanding Magic line-up supports expectations for a strong finish to 2026 and continued growth in 2027.
3M reported Q3 2026 adjusted revenue of $6.6bn vs $6.6bn expected, up +4.2% y/y, and adjusted EPS of $2.50 vs $2.39 expected, up +12% y/y. The company raised its full-year 2026 adjusted EPS guidance to between $9.10 and $9.15 and projected adjusted sales growth of over +4.5%. In corporate developments, 3M expanded its commercial relationship with Amazon to deploy optical connectivity and data centre products, issuing warrants to Amazon to purchase up to 3,162,015 shares at $164.89 per share. The chief executive officer stated that the company achieved another quarter of strong performance driven by solid sales growth, margin expansion, double-digit EPS growth, and robust free cash flow.
MSCI reported Q3 2026 revenue of $892.0mn vs $886mn estimated, up +12.4% y/y, and adjusted EPS of $5.11 vs $5.02 estimated, up +14.3% y/y. Adjusted EBITDA rose +12% y/y to $554.8mn vs $551mn estimated, whilst operating income was $502.1mn vs $508.4mn estimated. Free cash flow dropped -9% y/y to $385.4mn vs $414mn expected. For full-year 2026, the group projected free cash flow between $1.485bn and $1.545bn alongside capital expenditure of $160mn to $170mn. In corporate developments, MSCI agreed to acquire First Street Technology and completed $552.3mn in share repurchases. The Chief Executive Officer noted that the company delivered strong financial and operating metrics, entering the fourth quarter with solid momentum and client engagement.
Northrop Grumman reported Q3 2026 revenue of $11.12bn vs $11.14bn expected, up +7% y/y, and adjusted EPS of $7.89 vs $7.18 expected, up +3% y/y. Operating income reached $1.27bn vs $1.2bn expected, whilst the operating margin was 11.4%. Segment performance was led by Aeronautics Systems up +14% y/y to $3.58bn and Defense Systems up +12% y/y to $2.31bn, alongside Mission Systems up +2% y/y to $3.16bn and Space Systems up +2% y/y to $2.75bn. Net awards totaled $16.4bn, bringing the order backlog to $109.6bn. For full-year 2026, the company raised adjusted EPS guidance to between $29.35 and $29.75 vs $28.98 expected, with revenue projected at $43.75bn to $44.25bn. Management stated that the record backlog and portfolio investments would sustain sales and earnings growth into 2027.
RTX reported Q3 2026 revenue of $24.97bn, up +11% y/y vs $24.08bn expected, and adjusted EPS of $2.26, up +33% y/y vs $1.78 expected. Segment revenue saw Pratt & Whitney generate $9.23bn, up +10% y/y, Collins Aerospace produce $8.38bn, up +10% y/y, and Raytheon achieve $8.03bn, up +14% y/y. Free cash flow reached $2.12bn. RTX raised full-year 2026 guidance, lifting expected revenue to between $97.0bn and $97.5bn vs $96.07bn expected, and adjusted EPS to between $7.65 and $7.75 vs $7.24 expected. Operationally, the group secured multi-year production contracts for Tomahawk and AMRAAM missiles. Management stated that product demand remained robust with over $81bn in new commercial and defence awards driving a record backlog of $340bn.
Vicor Corporation reported Q3 2026 revenue of $197.1mn vs $184mn expected, up +78.5% y/y, and EPS of $1.33 vs $1.29 expected, rose +111% y/y. Net income reached $63.3mn vs $60.8mn expected, up +124% y/y, whilst gross margin expanded to 68.3%. Operating cash flow rose +81% y/y to $69.7mn, and backlog increased up +166% y/y to $406mn. Vicor granted its first VPD licence to an AI OEM at Stage-2 royalty rates and announced plans for two additional sites to increase capacity by nearly 5X relative to Fab-1, noting an ITC patent infringement investigation is driving licensing inquiries. Management commented that capacity expansion is necessary in view of demand and industry trends.
SpaceX reported Q3 2026 revenue of $14.58bn, up +161% y/y vs $12.87bn expected, and GAAP EPS of $0.35 vs $0.16 expected, with net income reaching $4.40bn. Segment performance was driven by Super Intelligence revenue of $7.56bn, up +830% y/y, and Connectivity revenue of $5.25bn. Management guided Q1 2027 revenue to between $33bn and $37bn. In corporate activity, special committees were formed at SpaceX and Tesla to evaluate a potential merger between the two companies. In analyst coverage, Evercore ISI raised its price target to $275 from $230, while Morgan Stanley reiterated an Overweight rating with a $300 price target. Chief Executive Officer Elon Musk stated that annual recurring revenue could reach between $500bn and $1trn by the end of 2027.
Netflix reported third-quarter revenue of $12.87bn vs $12.87bn expected, up +12% y/y, and EPS of $0.87 vs $0.82 expected. Free cash flow was $2.88bn vs $3.22bn expected. For the fourth quarter, Netflix forecast revenue of $13.44bn vs $13.51bn expected and EPS of $0.67 vs $0.73 expected. Full-year advertising revenue guidance was trimmed to $2.7bn from $3.0bn. Prior to the report, the company reduced its workforce by -6%, cutting roughly 1,000 positions, appointed former Disney executive Peter Rice as Chief Content Officer, and announced plans to expand its advertising tier to 15 additional countries in 2027. The Chief Executive Officer stated that the company delivered on its quarterly forecast and expects to achieve full-year guidance.
Capital One reported third-quarter 2026 results after the market close, delivering net revenue of $16.3bn vs consensus expectations of $16.25bn. Adjusted EPS reached $6.69 vs $5.43 expected, whilst GAAP EPS rose +16% y/y to $5.61, supporting net income of $3.5bn. Credit metrics outperformed forecasts, with provisions for credit losses of $2.9bn vs $3.64bn expected and net charge-offs of $3.1bn vs $3.41bn projected. Quarterly integration expenses included $338mn for Discover and $47mn for Brex. The Chief Executive Officer stated that the Discover integration continues to progress well with solid delivery of expected synergies, adding that the bank intends to step up marketing to compete against rivals.
United Airlines reported its Q3 2026 financial results after market close, posting operating revenue of $17.88bn vs $17.89bn expected, up +17.4% y/y, and adjusted EPS of $2.54 vs $2.59 expected, down -8.6% y/y. Performance was pressured by a $1.8bn y/y increase in fuel expenses, with average fuel prices up +60.3% y/y. Consequently, the airline cut its 2026 profit guidance and projected Q4 adjusted EPS of $0.50 to $1.50 vs $1.88 expected, despite forecasting Q4 revenue growth of over +20% y/y. Operationally, Starlink Wi-Fi was installed on more than 640 aircraft, alongside plans for 10 new international destinations. The chief executive stated that the quarterly results proved the resilience of focusing on brand loyalty and enhanced on-board product technology.
European Stock Indices
CAC 40 -0.38%
DAX -0.06%
FTSE 100 -0.29%
Commodities
Gold spot +0.06% to $4,122.53 an ounce
Silver spot +0.23% to $57.87 an ounce
West Texas Intermediate -1.80% to $101.79 a barrel
Brent crude -0.69% to $108.79 a barrel
Gold edged up on Tuesday on a weaker dollar and a drop in US yields. Spot gold was +0.06% to $4,122.53 per ounce.
Spot silver was also up, rising +0.23% to $57.87 per ounce.
Oil prices were down on Tuesday as traders weighed ongoing Middle East supply concerns against potential prospects for US - Iran talks and weaker US economic data.
Brent crude futures settled down $0.76, or -0.69%, at $108.79. Earlier in the session, the front-month contract reached $111.99, a five-month high.
The November contract for WTI crude, which expired on Tuesday, settled down $1.87, or -1.80%, at $101.79. That was down from the session high of $110.48. The more active December contract settled down $0.72 at $97.82 a barrel.
International Energy Agency (IEA) Executive Director Fatih Birol said on Tuesday that the organisation was ready to coordinate more emergency oil releases by member countries if needed. It is currently releasing diesel under existing plans to help cool surging prices.
The IEA announced last week that it would accelerate the release of crude and oil product volumes pledged in March, including more than 20 million barrels of diesel as soon as possible. Fatih said the release of the 20 million barrels of diesel depends on individual countries and market conditions. He did not give a timeframe for the release.
Meanwhile, US Energy Secretary Chris Wright said on Tuesday that his agency was talking about reopening every refinery they can. US refineries are running near full capacity and there is little room to quickly boost domestic output. Wright said the US is also working with India to increase refining output there to bring products to global markets.
According to Iran’s Nournews, Iran's President Masoud Pezeshkian discussed mediation efforts during a meeting with Pakistan's army chief Field Marshal Asim Munir in Tehran. This came as Israeli Prime Minister Benjamin Netanyahu said in a statement he is "committed to completing the elimination of the Iranian regime," and spoke with US President Donald Trump about it on Sunday.
Note: As of 4 pm EDT 20 October 2026
Currencies
EUR +0.22% to $1.1235
GBP +0.34% to $1.3377
Bitcoin +0.19% to $82,639.58
Ethereum +0.27% to $2,442.58
The US dollar fell on Tuesday along with oil prices and longer-dated Treasury yields as traders weighed rising tensions in the US-led war with Iran and the durability of strong capital inflows into US AI companies.
The dollar index fell -0.25% to 101.71. The euro was +0.22% to $1.1235. Sterling was up +0.34% to $1.3377.
The Japanese yen gained +0.21% to reach ¥158.14 per dollar. The yen jumped after an auction of longer-dated Japanese government bonds (JGBs) drew record demand.
Fixed Income
US 10-year Treasury -2.6 basis points to 5.115%
German 10-year Bund -5.8 basis points to 3.405%
UK 10-year Gilt -3.4 basis points to 5.390%
Treasuries rallied on Tuesday, with the benchmark 10-year yield ending the day -2.6 bps to 5.115%. This may be due to the drop in housing starts indicating a potential slowdown in the US economy, thereby removing some expectations that the Fed will raise rates at the October meeting despite higher core inflation. The 30-year US Treasury yield fell -5.5 bps to settle at 5.423%. The two-year US Treasury yield, which typically tracks Fed funds rate expectations, was -1.8 bps to 4.784%.
The US 2s10s yield curve stood at 33.1bps, down from Tuesday’s 37.5 bps.
Markets are pricing in a 82.8% probability that the Fed would keep rates unchanged at its 27 – 28 October meeting, up from 77.9% a week ago. They also assigned a 76.1% probability that the Fed funds target range would be at least 25 bps higher in December, according to CME Group's FedWatch Tool.
German government bonds also rallied on Tuesday, with the German 10-year yield declining -5.8 bps to 3.405%. At the front end, the two-year Schatz yield, which is more sensitive to policy rate expectations, fell -5.6 bps to 3.071%. At the long end, the 30-year yield -5.9 bps to 3.758%.
The yield spread between 10-year French OATs and German Bunds stood at 150.7 basis points.
The 10-year OAT yield was +0.5 bps to 4.912%.
The Italian 10-year yield was -1.6 bps on Tuesday to 4.547%. The spread between Italian BTPs and German Bunds was 114.2 bps.
Note: As of 4 pm EDT 20 October 2026
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
本文提供給您僅供資訊參考之用,不應被視為認購或銷售此處提及任何投資或相關服務的優惠招攬或遊說。金融商品交易涉及重大損失風險,可能不適合所有投資者。過往績效不代表未來表現。
 回到所有洞察資訊


由專業人士建立。為專業人士打造。
