
Is France just the starting point?


 S&P 500 +0.41% to 7,690.73 US 10-year yield +5.8 basis points to 5.141% Spot gold -0.05% to $4,140.10 an ounce DXY +0.15% to 102.01
What to look out for today
Companies reporting on Tuesday, 20th October: 3M, GE Aerospace, General Motors, Philip Morris International, Halliburton, Capital One Financial, Northrop Grumman, Synchrony Financial, Intuitive Surgical, Netflix, SpaceX, United Airlines, Omnicom Group, Hasbro, East West Bancorp, Keycorp
Key data to move markets today
EU: German PPI, German ZEW Current Situation and Economic Sentiment surveys, Eurozone Economic Sentiment survey and a speech by Bank of Spain Governor José Luis Escrivá
UK: Average Earnings, Claimant Count, Claimant Count Rate, Employment Change and ILO Unemployment Rate
USA: ADP Employment Change 4-week Average, Building Permits, Housing Starts and Pending Home Sales
Global Macro Updates
Europe at the precipice? Protests across Europe over high costs of living and other economic concerns have turned increasingly disruptive, with violence breaking out in cities across France and also erupting in Milan, Italy. Italian Prime Minister Giorgia Meloni chaired an emergency meeting of her advisers Monday. Protests also took place in Belgium, Portugal and Albania.
On Monday the French government had to impose partial curfews on a number of French cities after the government admitted police had “lost control” during violent weekend protests around the country. However, French unions have called for a new round of strikes and rallies on 5 November.
The violent protests have put President Emmanuel Macron and prime minister Sébastien Lecornu under increasing pressure. This has been most obvious is the surge in French bond yields. The rise in the spread of French 10-year borrowing costs to Germany climbed as high as 147 bps on Monday, a level that has not been seen since the eurozone debt crisis in 2011 – 2013.
The government still has to pass a budget bill to rein in its exploding deficit. It is likely to reach 5.4% this year, well above the 3% mandated by the EU. France’s public debt is now a record $4 trillion, or 119% of GDP. This is the highest ratio since the end of World War II. Lecornu has proposed a 2027 budget that would only bring the deficit down to 5% of GDP from 5.4%, and faces a first critical vote in the National Assembly today. If this vote fails, then France could come under further pressure, including potentially needing to seek assistance from the International Monetary Fund as well as the ECB. Additionally if the surge in borrowing costs for France continues, it could affect borrowing conditions across the region, particularly in highly indebted countries such as Italy, Greece and Belgium.
However, most eurozone economies are in better shape than they were during the last debt crisis and are less reliant on foreign funding in terms of the average current account deficit. There is also the ECB’s Transmission Protection Instrument, its first line of defence against “unwarranted, disorderly market dynamics.” To counter surges in yields that fit that description, the ECB can buy government bonds with a maturity of up to 10 years. There is no limit to the size of those purchases. Technically, this mechanism is not supposed to be used for countries that are in breach of the European Union’s budgetary rules—that is, subject to an excessive deficit procedure. Yet, as noted by The Wall Street Journal, as long as a government is trying to get its finances back on track and following the advice of the European Commission, it may be eligible for help.
US Stock Indices
Dow Jones Industrial Average -0.07%
Nasdaq 100 +1.17%
S&P 500 +0.41%, with 7 of the 11 sectors of the S&P 500 down
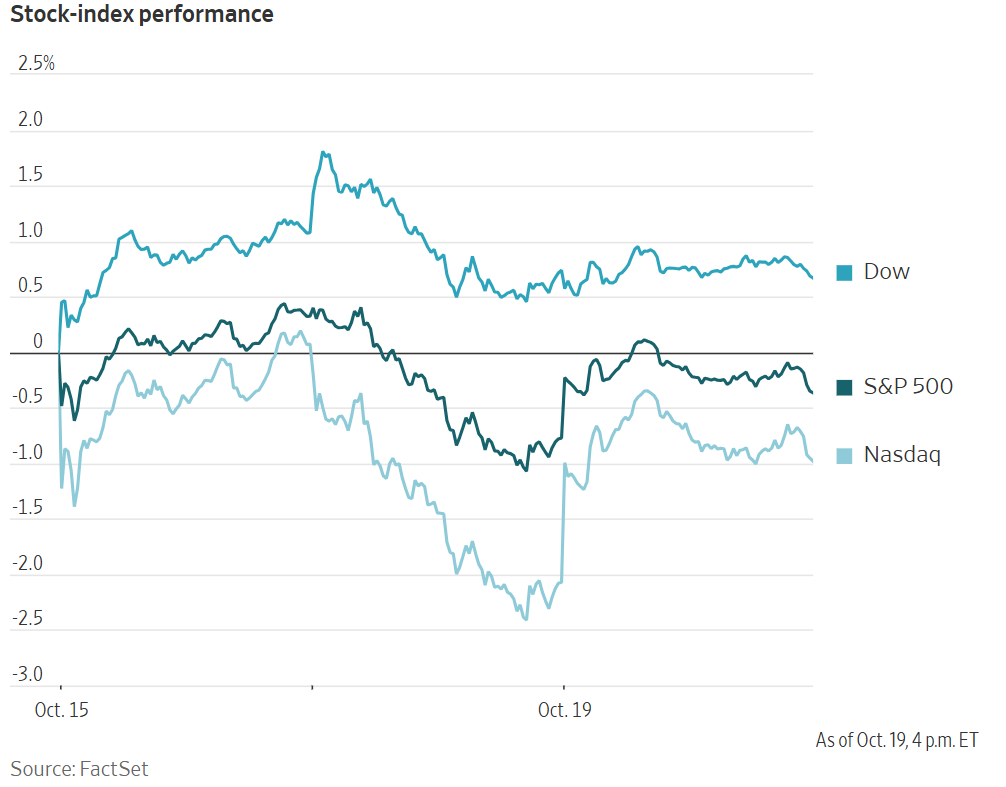
US equity indices were up on Monday as AI-related stocks rebounded from last week's sharp selloff. Semiconductors were among the day's biggest winners. The PHLX Semiconductor Index climbed 1.6%, ending an eight-session losing streak, its longest since the 2008 financial crisis.
The Dow Jones Industrial Average fell 36.38 points, or -0.07%, to 51,966.03, the S&P 500 rose 31.29 points, or +0.41%, to 7,690.73 and the Nasdaq Composite gained 290.85 points, or +1.11%, to 26,430.89.
In corporate news, Nscale Ltd was said to be in talks to sell computing power to Anthropic PBC in a deal that could be worth about $45 billion.
Amazon said it was introducing a new tool that allows its custom AI chips to run code written in the most popular AI coding language without modifications. It also said the software will be publicly released as a free and open-source offering. It was up +5% after Morgan Stanley named it as its "top pick."
Walmart’s sale of US and Canadian dollar bonds is expected to raise about $6.5 billion. The world’s largest retailer is seeking to diversify its funding sources amid a spending spree.
Kimberly-Clark raised $4.9 billion from its bond sale. The funds are expected to go towards its pending acquisition of Tylenol maker Kenvue Inc.
Intel shares climbed after J.P. Morgan Chase upgraded the stock to "neutral" from "underweight."
Corporate Earnings Reports
Posted on Monday, 19 October from The Pulse, our real-time AI-driven news tool. Available exclusively on the EXANTE Web Platform
Cleveland-Cliffs reported Q3 2026 revenue of $5.61bn vs $5.72bn expected, up from $4.73bn in the prior year. EPS was $0.26 vs $0.19 expected, with adjusted EPS of $0.28. Adjusted EBITDA reached $612mn vs $594mn expected, compared to $143mn a year earlier. Steel shipments reached 4.2mn net tons with an average selling price of $1,177 per ton. For Q4, the company guided adjusted EBITDA to approximately $715mn vs $665mn expected, while forecasting full-year 2027 adjusted EBITDA to exceed $4bn. Operationally, Stelco galvanising lines were indefinitely idled while preserving around 2,000 Canadian jobs. The chief executive stated that Q3 was the company's strongest quarter in three years and expressed confidence that new contracts would drive 2027 adjusted EBITDA above $4bn.
Crown Holdings reported Q3 2026 revenue of $3.71bn vs $3.44bn expected, up +16% y/y, and adjusted EPS of $2.39 vs $2.26 expected, up +7% y/y. Segment income fell -1% y/y to $484mn, whilst global beverage can volumes rose +6% y/y. For FY26, Crown Holdings expects adjusted EPS of $8.35-$8.45 vs $8.41 expected and adjusted free cash flow of at least $950mn. For Q4, adjusted EPS guidance of $1.63-$1.73 missed consensus of $1.80. Operationally, groundbreaking on an Uttar Pradesh plant began in September, targeting commercial start-up in Q1 2028. Management stated that global beverage can shipments advanced by more than +6% in the quarter, propelled by double-digit growth in Asia, up +6% in North America, and up +4% across Europe.
European Stock Indices
CAC 40 -1.11%
DAX -1.18%
FTSE 100 -1.08%
Commodities
Gold spot -0.05% to $4,140.10 an ounce
Silver spot -0.04% to $57.07 an ounce
West Texas Intermediate +2.2% to $103.66 a barrel
Brent crude -0.3% to $109.55 a barrel
Gold fell again on Monday as the dollar strengthened and Treasury yields rose. There is also cautious sentiment ahead of the Federal Reserve's upcoming policy meeting on 27-28 October. Spot gold edged down -0.05% to $4,140.10 per ounce.
Spot silver fell -0.04% to $57.07 per ounce.
Oil prices were mixed on Monday after attacks by Yemen's Iran-aligned Houthis on a Yemeni military training camp and renewed attacks on Saudi energy, airport and military facilities.
Brent crude futures settled $0.31, or -0.3%, at $109.55 a barrel, after falling more than $3 earlier in the session as investors booked profits following last week's rally. WTI gained $2.25, or +2.2%, to settle at $103.66 a barrel, the highest settlement since 15 September. However, as noted by Reuters, the trade was relatively thin ahead of the 20 October expiry of the front-month contract. Trading activity was concentrated in the more liquid December contract, with more than 195,000 lots changing hands, compared with about 26,000 lots in the expiring November contract. The December contract settled at $98.54, down 0.5%.
Early on Monday, 53 people were killed in a Houthi attack and 200 were injured in an attack on a Yemeni government security force training camp in the energy-producing province of Shabwa, in coastal south-central Yemen.
Egypt said it stood ready to support Saudi Arabia against the Houthis. However, its parliament delayed a vote that would authorise the armed forces to assist the kingdom if requested until 26 October.
According to the US Department of Energy, stocks of crude oil in the US Strategic Petroleum Reserve fell to 282.7 million barrels last week, the lowest level since October 1982. The drawdown in stocks has been part of an US agreement to release 172 million barrels from the facility.
Note: As of 4 pm EDT 19 October 2026
Currencies
EUR -0.24% to $1.1212
GBP -0.20% to $1.3302
Bitcoin +0.10% to $81,855.74
Ethereum +0.11% to $2,394.69
The US dollar rose on Monday, boosted by AI stocks. The dollar index rose +0.15% to 102.01.
The euro fell on Monday as the riots in France added to concerns about the worsening fiscal outlook. The euro was -0.24% to $1.1212. Sterling was -0.20% to $1.3302.
The dollar appreciated against the Japanese yen, +0.34% to ¥158.54 per US dollar.
Fixed Income
US 10-year Treasury +5.8 basis points to 5.141%
German 10-year Bund +4.2 basis points to 3.463%
UK 10-year Gilt +7.0 basis points to 5.424%
Treasury yields rose on Monday after suffering its worst drop last week in seven months, with the benchmark 10-year yield ending the day +5.8 bps to 5.141% as fears around the impact of higher interest rates on AI stocks eased. The 30-year US Treasury yield gained +4.8 bps to settle at 5.478%. The two-year US Treasury yield, which typically tracks Fed funds rate expectations, rose +5.0 bps to 4.766%.
The US 2s10s yield curve stood at 37.5 bps.
Markets are pricing in a 82.8% probability that the Fed would keep rates unchanged at its 27 – 28 October meeting, up from 79% a week ago. They also assigned a 76.1% probability that the Fed funds target range would be at least 25 bps higher in December, according to CME Group's FedWatch Tool.
German government bond yields rose on Monday, with the German 10-year yield, the eurozone benchmark, up +4.2 bps to 3.463%. At the front end, the two-year Schatz yield, which is more sensitive to policy rate expectations, rose +5.7 bps to 3.127%. At the long end, the 30-year yield climbed +3 bps to 3.817%.
The yield spread between 10-year French OATs and German Bunds stood at 144.4 basis points, after reaching 146 bps, its highest in two weeks.
The 10-year OAT yield surged +12.3 bps to 4.907%, the biggest one-day rise in almost a month as concerns grew about the extent of domestic unrest, with thousands of people arrested and shops looted over the weekend. The central government asked some local authorities to impose curfews on Monday, and Prime Minister Sebastien Lecornu did not rule out declaring a state of emergency.
France’s CDS rose 5 bps from Friday's close to around 82 bps. Although this is still below the 2 October high of 89 bps, it shows that investors are increasingly worried by France’s ability to pay its debts. The ratings agency Moody's is expected to issue a new review of France's credit rating this Friday, which could result in a downgrade, putting further pressure on France’s bonds.
Investors are concerned that the surge in French yields could spill over to other heavily indebted eurozone countries including Italy. The Italian 10-year yield was +9.8 bps on Monday to 4.563%. The spread between Italian BTPs and German Bunds was 110 bps.
Note: As of 4 pm EDT 19 October 2026
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
本文提供給您僅供資訊參考之用,不應被視為認購或銷售此處提及任何投資或相關服務的優惠招攬或遊說。金融商品交易涉及重大損失風險,可能不適合所有投資者。過往績效不代表未來表現。




由專業人士建立。為專業人士打造。
