

Earnings Scoreboard - The Quality of the Beat


Horacio Coutino, Multi-asset Strategist
Investor Lens
Q3 earnings season opens today in the customary way, with the biggest banks first through the door. However, almost nothing else about the backdrop is customary. This season begins with a ten-year Treasury yield at its highest level in roughly a quarter of a century, crude oil above one hundred dollars a barrel and a labour market that has spent the summer losing momentum. It is a quarter in which the corporate sector has been asked to keep compounding while the cost of capital, the cost of energy and the cost of labour-market insurance all moved against it at once.
- The expectations bar has continued to rise. According to FactSet, the blended Q3 earnings growth rate for the S&P 500 stood at 29.6% as of 9 October, up from 29.2% at the end of September and from 26.7% at the end of June, on expected revenue growth of 12.3%.
- Of the 116 companies that issued forward guidance, 72, or 62.1%, guided positively, against a five-year average closer to 40.0%. This is the highest quarterly total since FactSet began tracking positive S&P 500 EPS guidance in 2006, surpassing the previous record of 65 in Q2 2021.
- Of the 19 S&P 500 members that have already reported, 16, or 84.2%, beat the mean earnings estimate, by an aggregate 4.9%, and FactSet's own arithmetic suggests that, if the historical pattern of beats holds, the quarter could ultimately print earnings growth above 36.0%.
- Capital-markets momentum is not yet synonymous with a broad recovery. Strong equities and financing revenue would reward Goldman Sachs, Morgan Stanley and JPMorgan Chase, but advisory completions, underwriting and commercial lending are the better evidence that corporate confidence is extending beyond volatility and the AI investment complex.
- More capital freedom means less room for excuses. Wells Fargo must prove that post-cap growth can outrun margin dilution, while Citi must convert remediation spending into sustainable return on tangible equity (RoTE) and larger distributions. Across the group, disciplined deployment, and not the mere existence of surplus capital, will determine the rerating.
The week ahead
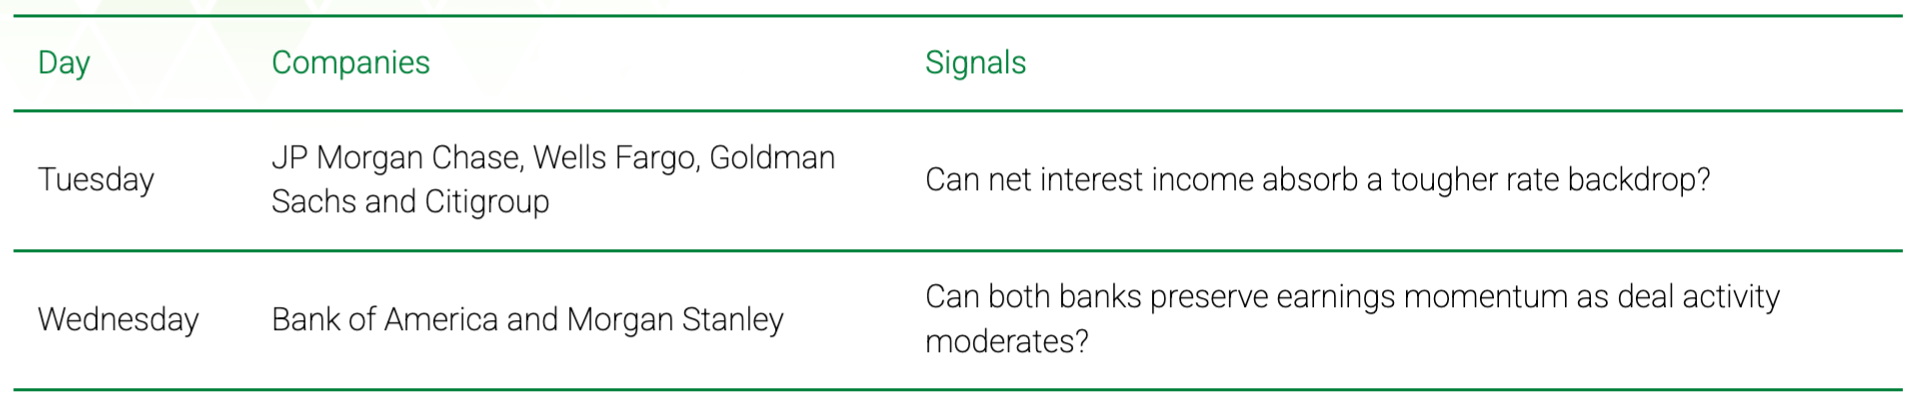
Questions earnings will answer
Can higher rates remain an earnings tailwind once their second-order effects arrive?
The first phase of the higher-rate cycle was comparatively straightforward for banks. Asset yields reset upward, securities portfolios gradually repriced and net interest margins expanded. The next phase is less generous. Depositors are more attentive to yield, Treasury volatility affects capital and liquidity management, corporate financing becomes more expensive and borrowers eventually confront the cumulative cost of carrying debt at higher rates.
This week’s reports will show where each institution sits along that transition. Bank of America offers the clearest test of the capacity of fixed rate asset repricing and balance sheet optimisation to sustain net interest income (NII) growth above the increase in deposit expense. Wells Fargo will show if renewed loan growth can secure attractive funding following the removal of its asset cap. JPMorgan will demonstrate the ability of its deposit scale, lending breadth and fee income to preserve superior returns despite elevated expenses.
The capital-markets firms provide the complementary view. Goldman Sachs and Morgan Stanley benefit when rate volatility increases trading activity. Yet, prolonged high yields can delay deals, reduce private-market realisations and pressure leveraged borrowers. A strong trading quarter can therefore coexist with a less favourable medium-term environment for investment banking and alternative assets. The income statement may celebrate precisely the volatility that the balance sheet and pipeline have reason to fear.
Credit is the delayed variable. Current indicators remain broadly benign, but aggregate stability can conceal deterioration among lower-income consumers or highly leveraged corporate borrowers. Card charge-offs at JPMorgan Chase, Citi and Bank of America will reveal if household normalisation can remain orderly. Private-credit commentary from Goldman Sachs and Morgan Stanley will indicate whether stress is migrating toward less transparent corners of the financial system.
Capital is being released. What will the Big Six do with it?
The regulatory cycle has shifted decisively toward relief. The stress capital buffers established by this year’s supervisory stress tests took effect on 1 October. The broader agenda also points to lower binding capital requirements for the largest institutions through a revised Basel III endgame proposal, adjustments to the enhanced supplementary leverage ratio and a review of the global systemically important bank surcharge.
The banks have already begun to act. Goldman Sachs raised its quarterly dividend to $5.00 and repurchased $4 billion of stock in Q2. Morgan Stanley increased its dividend by fifteen percent. According to its Q2 call, Citigroup launched a larger repurchase programme and planned a dividend increase. Excess capital is now a strategic variable instead of a defensive cushion. The market will scrutinise the trajectory of each bank’s Common Equity Tier 1 (CET1), its highest-quality, core capital mainly composed of ordinary common stock and retained earnings, buyback pace and appetite for acquisitions. JPMorgan’s view that its threshold for acquisitions is very high offers an instructive reminder that the largest balance sheet in American banking is not rushing to deploy its surplus.
Major earnings on the docket
JP Morgan Chase
Jamie Dimon’s capital fortress faces an earnings-quality test
JPMorgan Chase opens the season on Tuesday before the market opens, with results expected at 7:00 am EDT and the earnings call at 8:30 am EDT. Consensus calls for EPS of $5.93, compared with $5.07 a year earlier, up 16.9 % y/o/y, on Net Interest Income (NII) of $26.864 billion, up 11.5 % from a year earlier. RoTE is anticipated to be 20.8 % and the CET1 Capital Ratio, which measures a bank’s core equity capital against its total risk-weighted asset, 14.0 % compared to 14.1 % at the end of Q2. This level provides substantial excess capital, and investors will closely scrutinise management’s plans for buybacks, dividends and surplus deployment under the incoming regulatory regime.
The quarter begins from a position of considerable strength and the Commercial & Investment Bank (CIB) segment is where the intra-quarter guidance provided at the Barclays Global Financial Services Conference on 15 September set the highest bar. It is also the segment where a beat requires the most interpretation. Active equity markets, healthy financing demand and an improving investment banking pipeline should support revenue. However, trading driven upside is less durable than gains from advisory completions, underwriting and payments. Investors will therefore be best served by distinguishing revenue generated by market volatility from revenue that signals renewed corporate confidence. For Q3, consensus is more conservative than the company’s guidance of mid-high teens growth y/o/y, as it anticipates CIB revenue to be $22.237 billion, increasing 11.8 % y/o/y.
Within Consumer & Community Banking (CCB), the most important signals will come from card balances, spending, payment rates and charge-offs. Aggregate consumer expenditure may remain healthy even as lower-income borrowers encounter stress, so the distribution of credit performance matters more than the average. Deposit balances and pricing will also determine whether higher asset yields continue to produce incremental NII or are increasingly passed through to customers. For Q3, the Street anticipates CCB revenue to increase 6.1 % y/o/y to $20.658 billion.
Expenses are the principal obstacle to an untidy beat. Following JPMorgan’s upward revision to its 2026 expense outlook in Q2, revenue growth must remain broad enough to prevent costs from becoming the defining feature of the quarter. A strong print would combine better-than-expected NII with broad-based markets growth, sustained investment-banking momentum, stable consumer credit and disciplined expense guidance.
Wells Fargo
Post-cap growth is welcome, but profitable growth is the actual assignment
Wells Fargo also reports Tuesday before the open, with results around 7:00 am EDT and the call at 10:00 am EDT. The bank is expected to earn $1.85 per share in Q3, up from $1.66 a year earlier, on NII of $12.659 billion, up 5.9 % y/o/y. For Q3, RoTE is expected to reach 16.0 % from 17.7 % in Q2 and 15.2 % a year prior, while the CET1 Capital Ratio is projected to be 10.1 %, lower than Q2’s 10.3 %.
The removal of Wells Fargo’s regulatory constraints has shifted the company into an early multi-year organic growth phase, with management seeing substantial runway across consumer banking, cards, wealth, commercial banking and the corporate and investment bank. Q2 offered early evidence: average loans increased 12.0 % y/o/y, NII rose 5.2 % and investment-banking fees increased 34.9 %.
However, that growth has come at the cost of a narrower net interest margin (NIM), which fell to 2.43 % from 2.68 % a year earlier and 2.47 % in Q1 as the bank added lower-yielding assets and more expensive funding. At the Barclays Global Financial Services Conference, CFO Mike Santomassimo maintained full-year NII guidance of approximately $50 billion and said Q3 NIM was expected to be flat or down one basis point (bp), an improvement from the previous forecast of a three-to-four bps decline. He also said capital returns should continue through buybacks as Wells Fargo manages CET1 at 10.0 % – 10.5 %. The pace will partly depend on final US capital rules, which management still expects to be favourable for risk-weighted assets.
Wells Fargo regained the freedom to grow. This quarter begins to answer if it has also regained the ability to choose growth selectively, outrunning the margin dilution growth can bring.
Goldman Sachs
The quarter after the exceptional quarter
Goldman Sachs reports Tuesday before the open, with results expected at 7:30 am EDT and the call at 9:30 am EDT. Consensus calls for EPS of $12.86, above the $12.25 a year earlier. For Q3, the Street projects total revenue to reach $16.833 billion, up 10.9 % y/o/y, RoTE is anticipated to be 16.2 % from 15.1 % a year earlier and the CET1 Capital Ratio is pencilled in at 12.7 %. The y/o/y comparison appears manageable; the sequential comparison is considerably less so. Q2 produced record EPS of $20.98 and RoTE of 25.3 %, driven by exceptional Equities performance under the Global Banking & Markets segment.
For Q3, Chief Executive David Solomon's mid-September characterisation indicated that Fixed-income, Currency and Commodities (FICC) activity will soften sequentially, while Equities should remain comparatively strong. This places considerable weight on the composition of trading revenue. Equities Q3 revenue is anticipated to be $5.052 billion, following Q2’s record of $7.416 billion and up 35.2 % y/o/y from a year earlier. FICC Q3 revenue is expected to increase 6.3 % y/o/y to $3.689 billion, a decline of 19.7 % sequentially from Q2.
Investment banking will be the second major determinant. The advisory pipeline has improved, and capital formation linked to AI, infrastructure, power and large strategic transactions remains active. Q3 Revenue for the segment in Q3 is pencilled in at $2.736 billion, up 3.0 % y/o/y and declining 19.4 % q/o/q. Finally, Asset & Wealth Management is central to Goldman’s attempt to make its earnings less cyclical. The firm ended Q2 with assets under supervision reaching a record $4 trillion and alternatives assets of $459 billion after raising a record $59 billion from third parties during the period. The segment’s revenue for Q3 is expected to reach $4.536 billion. However, the segment also carries the most subtle risk. Higher rates, slower exits and concerns around private credit can delay realisations and performance income. Goldman can report strong assets under supervision while still experiencing weaker monetisation.
Goldman Sachs is the clearest listed read on capital-markets activity and the strongest test of whether the record trading results of the first half can be sustained in a less volatile tape.
Citigroup
Above eleven, the return target finally within reach
Citigroup completes Tuesday's docket before the open, with results at 8:00 am EDT and the call at 11:00 am EDT. Consensus calls for Q3 EPS of $2.65, compared with $1.86 a year earlier. NII is anticipated to increase 11.3 % y/o/y to $16.629 billion, while RoTE is pencilled in at 10.6 % from 8.7 % a year earlier, and the CET1 Capital Ratio is projected to be 12.6 %, from 12.8 % in Q2. Investors should note that Citigroup restructured its segment reporting from the first quarter of 2026, dissolving the former US Personal Banking segment, moving retail banking into Wealth and reporting the remainder as US Consumer Cards, so comparisons with prior-year segment data require care.
Chief Executive Jane Fraser's transformation programme has reached the stage at which its returns are visible and the five segments describe a bank that has become, at its core, a global transaction-services franchise with a capital-markets business attached. Services, Citi’s highest-quality franchise, is expected to report $6.551 billion in revenue. Markets should benefit from equities and client activity, although the same durability question that applies to peers is relevant here. Q3 Markets revenue is projected at $6.063 billion. Additionally, Banking will provide the clearest read on whether the capital-markets recovery is broadening, with the consensus segment’s revenue estimate at $1.326 billion.
At the Barclays Global Financial Services, CFO Gonzalo Luchetti guided Q3 Markets revenue up by a mid-single-digit percentage, investment banking up by a low single digit with some upside and, more importantly, full-year RoTE a little above 11.0 %, exceeding the 10 % to 11 % target range that had long anchored the transformation narrative.
Capital returns have become central to the equity story since Citi announced a larger repurchase programme and a planned double-digit dividend increase in Q2. Share repurchases in 2026 are expected to exceed the roughly $13 billion completed in 2025, while the CET1 capital ratio should remain near current levels.
Investors will also scrutinise progress on the deconsolidation of Banamex, the Mexican consumer franchise whose eventual listing remains both a strategic objective and a regional milestone for Latin American investors. Deconsolidation is expected in early 2027, once Citi’s ownership falls below fifty percent. The ideal quarter would contain no drama: broad core-business growth, stable credit, credible expense restraint and larger capital returns. That may sound undemanding, but for Citi, consistency is itself the rerating catalyst.
Bank of America
A net-interest-income story with a capital-markets complication
Bank of America reports Wednesday before the open, with results expected at 6:45 am EDT and the call at 8:30 am EDT, the same minute the September CPI report crosses the tape. Consensus expects EPS of $1.10, up 3.6 % from $1.06 a year earlier, and NII of $16.505 billion, increasing 8.4 % y/o/y. Q3 RoTE is projected at 15.2 %, with the CET1 capital ratio at 11.1 %.
Chief Executive Brian Moynihan has done investors the courtesy of lowering the bar in advance. At the Barclays Global Financial Services, he guided Q3 investment banking fees to between $1.6 billion and $1.8 billion against $2.013 billion a year earlier, citing an industry fee pool down about ten percent. He described sales and trading as relatively flat against the prior year's $5.361 billion. The shares, and those of the sector, fell that day.
However, the equity story depends more on NII and its deposit franchise than on capital markets. Management guided full-year NII growth to the upper end of its 6 % to 8 % range, with quarterly NII of at least $16 billion, and reaffirmed its medium-term net-interest margin target of 2.3 %, compared with the 2.1 % Q3 consensus. Repricing the bank’s large portfolio of fixed-rate securities and loans, many originated at the low yields of 2020 and 2021, is the main driver, with a steeper curve accelerating the process.
Fixed-rate asset repricing, loan growth and balance-sheet optimisation should offset higher deposit costs. Alongside the buyback programme, the market reaction will depend on card credit quality and operating leverage, with revenue growth outpacing expense growth.
Softer Q3 capital-markets guidance at the mid-September conference weighed on sentiment across the banking sector, reflecting lower investment-banking fee expectations and slower international and Asian prime-brokerage financing. Still, most analysts covering BofA continued to highlight strong pipelines, broad commercial-loan growth tied to corporate CapEx, rate-driven NII expansion and a potential recovery in operating leverage in Q4.
Morgan Stanley
Can wealth compound when the tailwind fades?
Morgan Stanley also reports Wednesday before the open, with results at 7:30 am EDT and the call at 9:30 am EDT. The Street expects Q3 EPS of $2.93, compared with $2.80 a year earlier, on total revenue of $19.927 billion. RoTE is pencilled in at 22.4 % and the CET1 Capital Ratio at 14.3 %.
Estimates point to continued strength in Wealth Management and Institutional Securities, led by sustained momentum in Equities and partly offset by normalisation in Fixed Income and more moderate Investment Banking activity.
Institutional Securities remains the principal source of quarterly earnings volatility. Revenue is projected to decline 11.9 % q/o/q in Q3, following a 44.5 % y/o/y increase in Q2, while remaining 14.2 % higher y/o/y at $9.730 billion. Within the segment, Equity revenue is expected to rise 26.9 % y/o/y to $5.221 billion, while Fixed Income revenue is projected to increase 5.2 % y/o/y to $2.283 billion. Investment Banking revenue is expected to remain broadly stable at $2.114 billion, up 0.3 %. At the Barclays Global Financial Services Conference, Morgan Stanley Co President Dan Simkowitz said the firm expects the M&A and IPO recovery to extend for 18 to 24 months or longer. Activity remains well below trend, while private equity firms continue to hold substantial dry powder and a large backlog of assets awaiting monetization.
Wealth Management remains the firm’s strategic anchor. Revenue is expected to reach $9.043 billion, supported by a 42.7 % y/o/y increase in asset management revenue to $6.835 billion and a 13.7 % rise in net interest income to $2.265 billion. The business also represents Morgan Stanley’s largest long term growth opportunity. Its expansion from roughly 2.5 million to more than 20 million households remain at an early stage of monetisation, while workplace channels should continue to support advisor relationships and asset growth.
Investment Management revenue is expected to decline 12.7 % y/o/y to $1.442 billion, partly because the previous contribution from performancebased income will be difficult to repeat. Long term flows, fundraising for alternative assets and valuations in private markets will therefore provide more meaningful signals than the headline revenue figure.
DISCLAIMER: This article is provided to you for informational purposes only and should not be regarded as an offer or solicitation of an offer to buy or sell any investments or related services that may be referenced here. Trading financial instruments involves significant risk of loss and may not be suitable for all investors. Past performance is not a reliable indicator of future performance.
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
本文提供给您仅供信息参考之用,不应被视为认购或销售此处提及任何投资或相关服务的优惠招揽或游说。金融工具交易存在重大亏损风险,未必适合所有投资者。过往表现并非未来业绩的可靠指标。
 返回到所有洞察




由专业人士创建。 为专业人士。
