

Crude assumptions

Chart of the Day
Defeat is not deescalation
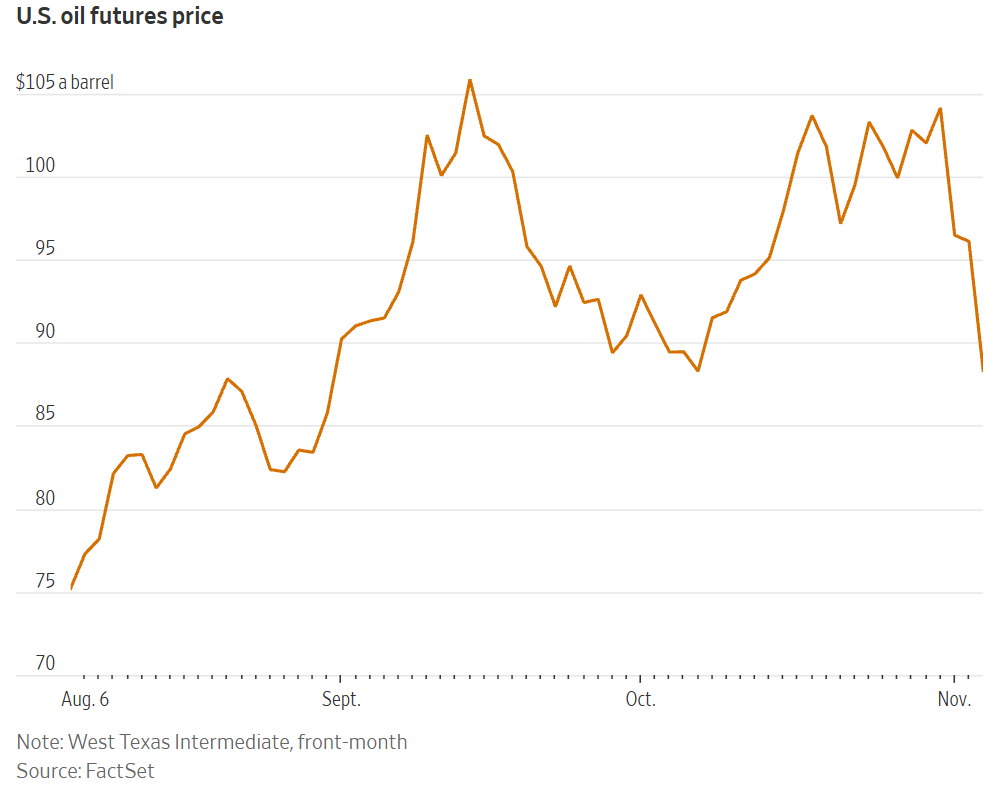
Oil markets have embraced a familiar proposition. Political pressure will eventually force President Trump to back down, with the retreat in crude prices reflecting expectations of a faster resolution with Iran. His assurance that Washington has no immediate plans for fresh strikes has reinforced that view. Yet an electoral setback is neither a peace agreement nor an inventory rebuild.
The bearish case has substance. Recovering Gulf exports have pushed the market back into an estimated surplus of 1.1 million barrels a day in September and 1.4 million in October. But improving supply flows should not be confused with restored resilience, particularly when depleted inventories leave little protection against renewed disruption.
Across the GCC, repairing damaged energy infrastructure and restoring supply security remain lengthy undertakings. Aramco’s chief executive has warned that replenishing global stockpiles could take up to two years, while repayment of Washington’s emergency oil loans extends into late 2028. The market has regained barrels, not its margin for error.
Domestic weakness also offers no guarantee of restraint abroad. With his legislative agenda increasingly constrained, the US President retains substantial influence over foreign policy, making external confrontation an available outlet for presidential power. The need to avoid appearing defeated could encourage a more aggressive posture towards Tehran, particularly if Iran interprets the election result as diminished American resolve. Markets may be pricing political necessity as diplomatic inevitability. That equivalence could prove expensive.
Equities
US markets closed sharply higher on Wednesday as the Democrats' win of both the House and Senate eased political uncertainty and boosted risk appetite. AI stocks performance was split, with chipmakers and data centre operators falling, while cash-rich tech companies rose on hopes that cash demands would also slow alongside the pace of the AI buildout. The Philadelphia SE Semiconductor index hit a six-month low, dropping 3.1%, while Microsoft, Amazon, Alphabet and Meta all rose. Elon Musk-led SpaceX and Tesla were down as were defence stocks Northrop Grumman and Lockheed Martin as President Trump's $1.5 trillion defence budget request could now face Congressional opposition.
- S&P 500 7,688.62 +1.58%
- Nasdaq Composite 25,736.51 +1.44%
- Dow Jones Industrial 1,569.40 +3.03%
- DAX 26,437.67 +2.22%
- CAC 40 8,177.89 +1.96%
- FTSE 100 10,829.21 +1.79%
Currencies
The dollar weakened against most currencies as yields on long-dated Treasuries moved lower.
- DXY 101.52 -0.36%
- EUR/USD $1.1227 +0.30%
- GBP/USD $1.3471 +0.44%
- USD/JPY ¥158.41 +0.18%
- Bitcoin $80,178.97 +3.00%
- Ethereum $2,417.17 +5.43%
Fixed Income
Global yields fell on Wednesday following the Democrats sweep in the midterm elections and the consequent plunge in oil prices. The two-year Treasury yield fell to 4.581%, its lowest level since early September. The gap between the two- and 10-year Treasury notes flattened to a positive 30.4 basis points.
Inflation expectations also eased with Derivative markets pricing inflation one year ahead at around 2.1%, down from 2.4% Tuesday, according to LSEG data. The US Treasury Department changed its language regarding future auction sizes that appears to suggest larger sales of short- and intermediate-dated debt and possible cuts to longer-dated auctions.
- US Treasury 10-year -7 bps 4.885%
- German Bund 10-year -4.9 bps 3.290%
- UK Gilt 10-year -12.7 bps 5.130%
- France OAT 10-year -12.1 bps 4.816%
- Italy 10-year -10.2 bps 4.328%
Commodities
Gold surged on Wednesday, experiencing its highest daily gain since mid-August on a weaker dollar and on expectations that the Democrats control of Congress will result in legislative deadlock, slowing the economy and easing pressure on the Fed to raise rates.
Oil prices plunged on Wednesday following the Democrat’s sweep of Congress on expectations that President Trump would not be able to launch a full scale attack on Iran and that he may instead be forced to quickly end the war with Iran.
- Spot Gold $4,061.61/oz +3.37%
- Spot Silver $52.26/oz +4.95%
- WTI crude $88.12 -8.3%
- Brent crude $94.62 -8.7%
Corporate Earnings Today
Companies reporting on Thursday, 5th November:
Key data to move markets today
The Bank of England (BoE) meets today and is widely expected to raise rates by 25 basis points.
 German Factory Orders, Eurozone PPI and speeches by ECB Executive Board members Piero Cipollone and Isabel Schnabel, ECB President Christine Lagarde, ECB Chief Economist Philip Lane and German Bundersbank President Joachim Nagel
 BoE Interest Rate Decision, Minutes, Monetary Policy Report, Monetary Policy Summary and a speech by BoE Governor Andrew Bailey
 Initial and Continuing Jobless Claims, Nonfarm Productivity, Unit Labour Costs and a speech by Cleveland Fed President Beth Hammack
 Labour Cash Earnings
FEATURED TODAY
Earnings Scoreboard: Cash conversion at the tollbooth
The repricing of balance-sheet velocity will be the connection between this week’s and last week’s earnings. Find out what to look for in this week’s earnings reports and how the results may move markets.
Renée Friedman, PhD
Editor-in-Chief, EXANTE
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
本文提供給您僅供資訊參考之用,不應被視為認購或銷售此處提及任何投資或相關服務的優惠招攬或遊說。金融商品交易涉及重大損失風險,可能不適合所有投資者。過往績效不代表未來表現。
 回到所有洞察資訊




由專業人士建立。為專業人士打造。
