
Will AI continue to shatter records?

 S&P 500 +0.70% to 7,676.77 US 10-year yield -1.4 basis points to 4.984% Spot gold +0.46% to $4,013.79 an ounce DXY +0.31% to 102
What to look out for today
Companies reporting on Tuesday, 27th October: Boeing, Centene, Coca-Cola, Corning, Ecolab, EQT, FirstEnergy, Freeport McMoRan, Novartis, PayPal, Seagate Technology, SoFiI Technologies, Robinhood Markets, Royal Caribbean, Sherwing-Williams, Teradyne, UPS, Visa, Waste Management Inc.
Key data to move markets today
EU: ECB Bank Lending Survey and a speech by ECB President Christine Lagarde
US: ADP Employment Change 4-week Average, Durable Goods Orders, Nondefence Capital Goods Orders, Housing Price Index, Consumer Confidence and New Home Sales
Global Macro Updates
Anthropic’s IPO challenge. On Monday Anthropic, creator of the Claude AI tool, published its IP prospectus on Monday detailing its revenue, losses and future expected spending. The prospectus explains how it plans to sustain growth and build AI systems able to reshape the global economy. In its S-1 paperwork it stated that it is planning to trade on the Nasdaq exchange under the ticker ANT.
A little over a year ago the company was valued at only $183 bn valuation. In May it was valued at around $965 bn. The prospectus showed revenues for the first half of 2026 of $16.3 bn, up from $1.2 bn over the same period the previous year. However, it warned that its revenue growth rate could decline and fluctuate from time to time.
Anthropic's net loss in the first half of 2026 was $80.7 bn, with more than $72 bn related to changes in the value of convertible notes as the company’s valuation increased. As noted by the Financial Times, most of the remaining losses came from an almost-$9 bn outlay on computing power and infrastructure.
Its operating loss for the first half was $693 million, down from $2.1 bn in the same period in 2025. Its adjusted operating income swung to a positive $1.62 bn compared with a loss of $1.85 bn a year ago.
Importantly, Anthropic revealed plans to aggressively increase its future spending, with commitments totalling close to $800 bn over the coming decade.
Additionally, the 94 page prospectus discussed a range of risk factors, including a “catastrophic AI-related incident.” In the filing's risk factors section, the company said that it had delayed pre-training of a new "frontier" base model to strengthen safeguards against the theft of model weights and intellectual property. Additionally, in the prospectus Anthropic noted various "risks to humanity" including attempts to "resist shutdown" and "conceal or manipulate information." It also emphasised the potential for its AI to "behave in unintended, misaligned, or autonomous ways."
In terms of share structure, Anthropic said it would issue five different classes of shares, including Class T shares that would give its Long-Term Benefit Trust the right to appoint the majority of its board and Class F stock that would hand its seven founders 50.1% of the voting power. All of this begs the question of what is the target valuation? The IPO is expected to take place before US Thanksgiving.
Anthropic is expected to be followed onto public markets next year by its main competitor, OpenAI.
US Stock Indices
Dow Jones Industrial Average +0.28%
Nasdaq 100 +1.09%
S&P 500 +0.70%, with 7 of the 11 sectors of the S&P 500 up
US equity indices advanced on Monday with tech stocks benefiting from Anthropic’s announcement of its planned IPO, as investors focussed on this week’s Fed, BoJ and ECB meetings and with more than a third of corporate earnings reports including from the biggest hyperscalers, expected. Semiconductor and chip-related companies helped fuel Monday’s gains, with Broadcom, AMD and Nvidia all up around +3. The broader Philadelphia chips index was +2.8% on the day, but is still down 12.2% on the month.
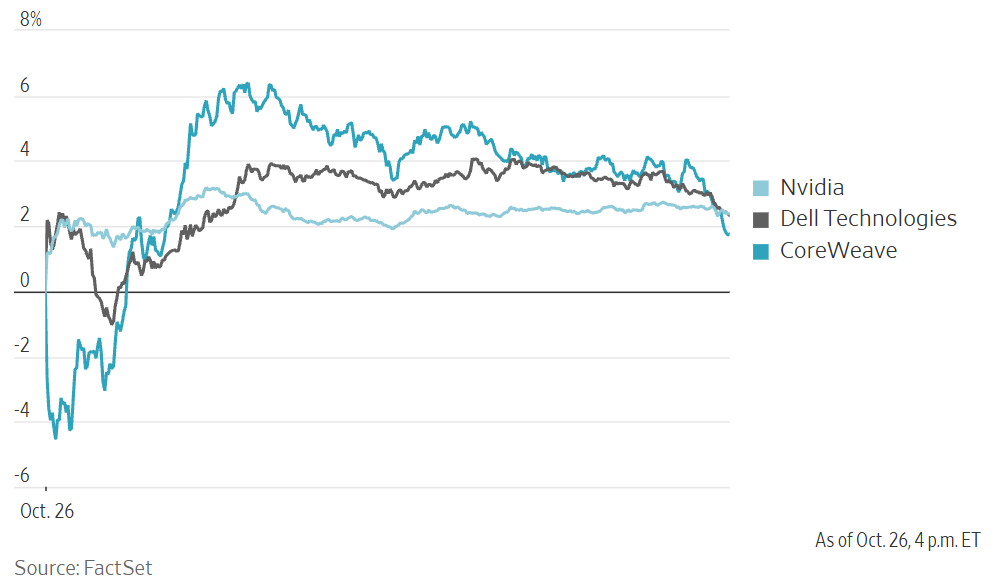
The Dow Jones Industrial Average was up 146.42 points, or +0.28%, to 52,361.58, the S&P 500 traded up 53.09 points or +0.70%, to 7,676.77 and the Nasdaq Composite rose by 214.04 points, or +0.83%, to 26,169.38.
In corporate news, Meta Platforms said on Monday it plans to raise up to $95 billion. It launched public offerings worth about $35 billion in common and preferred stock. It plans to launch a separate at-the-market share sale programme worth up to $60 billion, but that will not happen until the new non-voting Class C shares begin trading, which is expected in the first quarter of 2027. The company said it hadn’t finalised the timing and terms of the sale.
Microsoft said it is offering voluntary buyouts to about 60,000 employees, or more than a quarter of its global workforce, in an effort to contain costs and help fund its AI investments. Earlier this year the company offered voluntary buyouts to about 7% of its US workforce, or about 9,000 employees.
Corporate Earnings Reports
Posted on Monday, 26 October from The Pulse, our real-time AI-driven news tool. Available exclusively on the EXANTE Web Platform
Verizon reported Q3 2026 results with adjusted EPS of $1.31, beating consensus of $1.27 to $1.28 and rising +8.3% y/y, while operating revenue was $34.3bn, missing expectations of $34.74bn to $34.76bn despite growing +1.5% y/y. Postpaid phone net additions reached 406000, surging over +820% y/y, and broadband net additions hit 314000. Free cash flow reached $7.8bn, up +12.1% y/y. The company raised full-year 2026 guidance, projecting adjusted EPS of $5.04 to $5.06, postpaid phone net additions of 1.1mn to 1.2mn, and capital expenditure of $16.0bn to $16.5bn. Verizon also agreed an AI infrastructure and fibre-optic deal with Amazon Web Services valued at over $2.0bn. The Chief Executive Officer stated that customer-first offerings and loyalty programmes expand margins, reduce churn, and generate sustained cash flow.
Amkor Technology reported Q3 2026 revenue of $1.99bn vs $2.01bn expected and EPS of $0.76 vs $0.78 expected, with gross margin reaching 18.3% vs 19.1% expected. For Q4 2026, the company guided revenue between $1.9bn and $2.0bn vs $2.02bn expected, alongside EPS of $0.65 to $0.75 vs $0.76 expected. Full-year 2026 capital expenditure is projected at ~$2.5bn. In operational developments, Amkor entered a $1.3bn strategic agreement with NVIDIA to boost South Korean advanced packaging interposer wafer capacity by over +300% by the end of 2028. Management stated that the company is executing its strategy, advancing key customer programmes, and benefiting from expanding commitments that support disciplined investment to meet future demand.
Cadence Design Systems reported Q3 2026 revenue of $1.63bn vs $1.61bn expected, up +22% y/y, and adjusted EPS of $2.11 vs $2.05 expected, up +9% y/y. Segment growth saw Core EDA rise up +20% y/y, IP increase up +24% y/y, and System Design and Analysis expand up +30% y/y, driving order backlog to $8.2bn. The company also announced a new $2.5bn share repurchase authorization alongside the launch of Maestro, a portfolio of domain-specialized AI models. Cadence raised its full-year 2026 revenue guidance to between $6.39bn and $6.42bn, representing growth of up +21% y/y, and lifted adjusted EPS expectations to $8.37 to $8.43. Management stated that broad-based business momentum and technology leadership enabled the upgraded annual outlook.
Nucor reported its Q3 2026 financial results, with revenue rising up +32% y/y to $11.25bn vs consensus estimates of $10.83bn. Adjusted EPS increased to $5.80 vs $2.63 in the prior-year period. By segment, pre-tax earnings in Steel Mills reached $1.79bn vs $793mn y/y, Steel Products generated $465mn vs $319mn y/y, and Raw Materials posted $105mn vs $43mn y/y. For Q4 2026, the company expects earnings to be generally in line or modestly higher, driven by higher pricing and lower volumes in steel segments. The firm also returned approximately $629mn to shareholders via share buybacks and dividends. Leadership noted that ongoing capital projects and recent investments were expanding company capabilities and strengthening its position across attractive markets.
Rambus reported Q3 2026 revenue of $218.3mn, up +22% y/y, surpassing estimates of $213.2mn, and adjusted EPS of $0.84 vs $0.79 expected. Product revenue rose +22% y/y to $114.3mn, while cash from operations reached $102.5mn alongside $135.4mn in share repurchases. For Q4 2026, the company guided revenue of $227mn to $233mn vs $227mn expected and adjusted EPS of $0.84 to $0.92 vs $0.84 expected. Additionally, Rambus announced a collaboration with ChipAgents to accelerate chip design with agentic artificial intelligence. Management stated that the company continues expanding its product and intellectual property offerings to address growing performance requirements for next-generation artificial intelligence and data centre infrastructure.
Welltower reported third-quarter revenue of $3.72bn vs $3.60bn expected, and normalized FFO of $1.67 vs $1.63 expected, up +25% y/y, while EPS reached $0.54 vs $0.66 expected. Total same-store NOI grew +15.8% y/y, driven by seniors housing operating same-store NOI growth of +21.0% y/y. For the full year 2026, the group raised its normalized FFO guidance to $6.47-$6.53 vs $6.37 expected, and EPS guidance to $3.31-$3.37, alongside projected blended same-store NOI growth between +15.0% and +16.25%. During the quarter, Welltower completed $4.1bn in gross investments, including $2.7bn across 43 seniors housing properties, and ended the period with approximately $9.5bn in available liquidity.
Whirlpool reported its Q3 2026 financial results, posting revenue down -8.8% y/y to $3.68bn vs $3.92bn expected and an adjusted loss per share of -$0.21 vs earnings of $0.80 expected. Ongoing EBIT fell -46.1% y/y to $97mn vs $181mn expected. MDA North America sales reached $2.50bn vs $2.66bn expected, whilst SDA Global net sales fell -0.7% y/y to $286mn vs $322mn expected. Whirlpool lowered its full-year 2026 guidance, projecting revenue of ~$14.5bn vs $14.82bn expected, adjusted EPS of -$1.30 vs $1.55 expected, and ongoing EBIT of ~$293mn vs $518mn expected. Leadership noted that whilst the pace of recovery is slower than anticipated, ongoing actions establish a clear path for improvement in 2027.
European Stock Indices
CAC 40 +0.83%
DAX +0.91%
FTSE 100 +0.72%
Commodities
Gold spot +0.46% to $4,013.79 an ounce
Silver spot +0.16% to $53.98 an ounce
West Texas Intermediate -1.46% to $101.76 a barrel
Brent crude -0.78% to $115.81 a barrel
Gold rose on Monday due to investors positioning ahead of this week’s Fed meeting and on softer oil prices reducing some inflation worries.
Spot gold was +0.46% to $4,013.79 an ounce, rebounding from Friday's more than three-month low. US gold futures settled +0.8% higher at $4,038.40 per ounce.
Spot silver was +0.16% to $53.98 per ounce.
Oil prices fell on Monday after Friday's strong gains and on hopes that there may be some easing in tensions. On Sunday, Qatari mediators travelled to Tehran to try to de-escalate regional tensions in coordination with the United States, an official briefed on the situation said.
Saudi Arabia, Turkey and Pakistan were set to hold talks with Iranian officials in Tehran, said it was important to open channels for negotiations.
However, the Houthi’s said on Monday they had attacked Saudi Arabia's East-West crude oil pumping stations and Riyadh airport.
Brent crude futures settled -0.78% to $115.81 per barrel. WTI also fell, settling -1.46% to $101.76 per barrel.
Note: As of 4 pm EDT 267 October 2026
Currencies
EUR -0.21% to $1.1179
GBP -0.24% to $1.3344
Bitcoin -0.38% to $79,733.91
Ethereum -1.79% to $2,308.05
The dollar rose on Monday on safe haven purchases and on stronger US regional economic data, with the Chicago Fed National Activity index and the Dallas Fed's October manufacturing index both rising. The dollar index was +0.31% to 102.
The Japanese yen fell -0.43% to ¥157.46 per dollar.
The euro was down -0.21% against the dollar at $1.1179, but was +0.31% at ¥176.04.
Sterling fell -0.24% as investors nervously await the first budget from the UK’s new Chancellor of the Exchequer, John Healey, on Wednesday. With energy costs, inflation and bond yields all rising, markets will be looking closely to see if the Labour government will continue to raise taxes, which are already at the highest level since just after World War Two, or if spending cuts will be made.
Fixed Income
US 10-year Treasury -1.4 basis points to 4.984%
German 10-year Bund +0.6 basis points to 3.361%
UK 10-year Gilt -4 basis points to 5.330%
US Treasury yields were mixed on Monday.
The yield on the benchmark US 10-year note edged down -1.4 bps to 4.984%. The yield on the 30-year bond was down -2.7 bps at 5.298%.
The 2-year Treasury yield, which typically moves in step with interest rate expectations for the Fed, was up +3.2 bps at 4.714%.
The US 2s10s yield curve stood at 27 basis points, its narrowest in about a month.
The breakeven rate on five-year US Treasury Inflation-Protected Securities (TIPS) was at 2.454% after closing at 2.465% last week. The 10-year TIPS breakeven rate was at 2.341%, indicating the market sees inflation averaging about 2.3% a year for the next decade.
Markets are pricing in an 89.5% probability that the Fed will not hike rates on Wednesday, up from last week’s 81.2% probability. They also assigned a 73.9% probability that the Fed funds target range would be at least 25 bps higher in December, according to CME Group's FedWatch Tool.
France's 10-year OAT rallied on Monday after Moody’s decided not to downgrade it last Friday. It was -8.1 bps to 4.959%. Last week, it hit a 24-year high of 5.1415%.
The gap between German and French 10-year yields was 159.8 bps after hitting its widest level since 2011 last week at 177.7 bps.
Italy's 10-year BTP yield fell -9.3 bps to 4.487%. The spread between the 10-year Bund and the Italian BTP stood at 112.6 bps.
Germany's 10-year government bond yield was +0.6 basis point at 3.361%. Germany's 2-year Schatz yield, which is sensitive to changes in ECB policy expectations, was up +4.5 bps at 3.090%. At the long end, the 30-year yield was -0.8 bps to 3.682%.
The UK 10-year gilt dropped -4.0 basis points to 5.330%.
Note: As of 4 pm EDT 267 October 2026
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
本文提供給您僅供資訊參考之用,不應被視為認購或銷售此處提及任何投資或相關服務的優惠招攬或遊說。金融商品交易涉及重大損失風險,可能不適合所有投資者。過往績效不代表未來表現。
 回到所有洞察資訊




由專業人士建立。為專業人士打造。
