

Will it be Trump vs Fed again?

 S&P 500 -0.44% to 7,552.14 US 10-year yield +1 basis point to 5.01% Spot gold -0.69% to $4,263.19 an ounce DXY +0.63% to 100.31
Key data to move markets today
EU: Eurozone harmonised index of consumer prices, eurozone core harmonised index of consumer prices and a speech by ECB chief economist Philip Lane
UK: BoE Interest Rate Decision, BoE Minutes and BoE Monetary Policy Summary
USA: Building Permits, Initial and Continuing Jobless Claims, Housing Starts, Philadelphia Fed Manufacturing Survey and Pending Home Sales
JAPAN: National CPI
Global Macro Updates
Warsh’s hawkish warning. In a unanimous decision, the Fed raised rates 25 bps yesterday for the first time in more than three years. The new dot plot showed that 16 of 18 policymakers are pencilling in one additional rate increase this year. Fed Chair Warsh did not submit a projection. The Fed's policy statement and projections show the policy rate rising to the 4.00%-4.25% range by the end of this year and ending 2027 at the same level.
The statement accompanying the decision highlighted that more tightening is likely in the near future to effect a timelier drop in inflation. Inflation has been running well above the 2% target for more than five years. The committee’s projections indicated they did not anticipate inflation reaching the central bank’s target until 2029.
During the press conference following the FOMC decision, Warsh said, “Inflation is too high and has been for too long. Our decision comes at a time when the American economy appears to be strengthening.” He stressed that the hike removed a “dose of accommodation” from policy. Warsh also mentioned the strength of the US economy and labour market. He said, “The American economy appears to be strengthening. New hiring, private sector earnings, business capital investment — each of these markers has improved in recent months and is pointing in a good direction.”
Data from the Commerce Department earlier in the day showed that retail sales jumped 1.2% last month after a revised 0.5% drop in July, which was the first decline in nine months. At the same time, Labor Department data showed that import prices rebounded 0.7% last month after declining by 0.3% for two straight months.
White House spokesman Kush Desai said in a Fox News Interview, “Today’s rather unfortunate decision by the Federal Reserve to hike interest rates was not, from the administration’s point of view, backed by a particularly compelling economic case.” President Trump, who has long advocated for lower rates and a cheaper dollar, responded to the rate rise on his Truth Social platform, saying that “Interest Rates in the United States should be 1%, or less, because we are the Best Credit in the World — BY FAR”. He then added, “LOWER THE INTEREST RATES FOR THE UNITED STATES OF AMERICA, AND FAST!”
US Stock Indices
Dow Jones Industrial Average -1.21%
Nasdaq 100 +0.03%
S&P 500 -0.44%, with 8 of the 11 sectors of the S&P 500 down
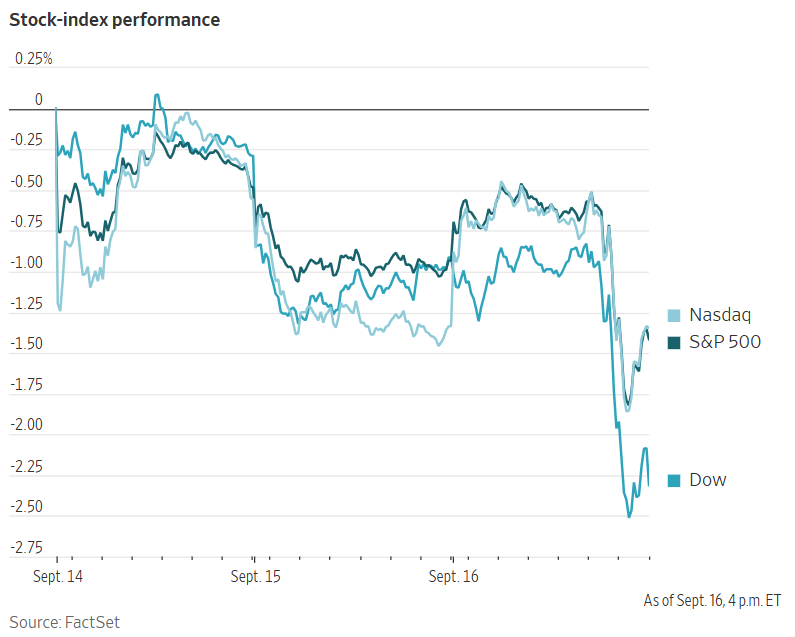
The Fed’s decision to raise interest rates by 25 bps yesterday sent stock prices lower. The Dow Jones Industrial Average fell 631.33 points, or -1.21%, to 51,461.78, the S&P 500 declined 33.59 points, or -0.44%, to 7,552.14 and the Nasdaq Composite was down 3.15 points, or -0.01%, to 25,978.43.
The Energy sector was weighed down by easing crude prices, falling 3.0%. Chevron and Exxon Mobil fell 2.9% and 3.5%, respectively, while Devon Energy and ConocoPhillips were down more than 5% each.
In corporate news, Boeing said it expects some testing on the new 777X model to spill into 2027, even as the US planemaker reiterated that deliveries of the long-delayed model are on track to begin next year. The stock slid 3.7% after Chief Executive Officer Kelly Ortberg said it is "taking longer than expected" to stabilise 737 MAX production rate at 47 aircraft per month.
United Airlines Holdings and American Airlines Group said they may need to cut more capacity in Q4 due to higher fuel prices as the war with Iran shows no sign of abating.
According to Reuters, SK Hynix is said to be in talks with Intel about a possible deal that would see it manufacture memory chips in the US by either leasing part of Intel's chipmaking facility in Ohio or by forming a venture with Intel and major cloud firms that are keen to lock in memory chip supplies.
JB Hunt Transport Services warned that higher costs for fuel and recruiting truckers will hurt its earnings.
European Stock Indices
CAC 40 +0.62%
DAX +0.53%
FTSE 100 +0.28%
Commodities
Gold spot -0.69% to $4,263.19 an ounce
Silver spot -0.36% to $62.73 an ounce
West Texas Intermediate -3.2% to $102.43 a barrel
Brent crude -2.7% to $105.83 a barrel
Gold prices fell on Wednesday after the Fed raised interest rates and flagged further increases in borrowing costs this year. This strengthened the dollar and put downward pressure on non-yielding bullion.
Spot gold fell -0.69% to $4,263.19 an ounce after having climbed more than 1% to a session high of $4,365.57 earlier in the day.
Spot silver was -0.36% to $62.73 per ounce.
Oil prices fell on Wednesday after reports that Saudi Arabia was offering additional crude cargoes through Oman, while a smaller-than-expected draw in US crude inventories also weighed on prices.
Brent crude futures fell $2.92, or -2.7%, to settle at $105.83 a barrel. WTI futures fell $3.40, or -3.2%, to close at $102.43.
According to Reuters, citing people familiar with the matter, Saudi Arabia is offering more loadings of crude oil to Asian refiners via ship-to-ship transfers off Oman's Sohar port.
Vessel passage through the Strait of Hormuz remained well below the 10-day average of 18, with only four ships passing through the Strait on Tuesday, down from seven a day earlier, preliminary shipping data showed on Wednesday.
The US Energy Information Administration (EIA) reported on Wednesday that crude oil stocks fell about 640,000 barrels last week, compared to expectations of a 1.62 million barrel draw. US gasoline and distillate inventories rose last week, EIA data showed.
Note: As of 4 pm EDT 16 September 2026
Currencies
EUR -0.68% at $1.1464
GBP -0.72% to $1.3379
Bitcoin -0.25% to $75,913.33
Ethereum -0.22% to $2,402.75
The US dollar jumped to its highest level since July after the Fed raised rates 25 basis points and signalled further tightening ahead.
The dollar index rose +0.63% to 100.31.
The euro was down -0.68% at $1.1464.
The Japanese yen weakened -0.77% against the dollar to ¥156.31 per dollar.
The British pound fell -0.72% to $1.3379, suffering its largest one-day percentage decline since 17 June. UK headline inflation accelerated to 3.1% in August from 2.9% in July. It was the highest rate for five months. The biggest contributors to the rise were rising petrol prices, with higher household energy bills also contributing, according to the Office for National Statistics (ONS). Core inflation remained at 2.6% and services inflation was also steady, at 3.4%.
The BoE is expected to keep rates on hold today, although expectations for at least one rate hike for this year remain.
Fixed Income
US 10-year Treasury +1 basis point to 5.01%
German 10-year Bund -3 basis points to 3.50%
UK 10-year Gilt -9 basis points to 5.30%
US Treasury yields were mostly higher on Wednesday after the Fed, as expected, raised interest rates by 25 bps to the 3.75%-4.00% range and suggested further increases in borrowing costs this year to control inflation.
The two-year Treasury yield, which typically moves in step with interest rate expectations for the Fed, hit 4.744%, its highest level since July 2024, before edging down to end the day +6.2 basis points at 4.738%.
The yield on the benchmark US 10-year Treasury note rose 1 basis point to 5.006%. The yield on the 30-year bond fell -1.3 basis points to 5.35%.
The breakeven rate on five-year US Treasury Inflation-Protected Securities (TIPS) was at +2.361% after closing at 2.417% on Tuesday.
The 10-year TIPS breakeven rate was at 2.337%. This signals that the market sees inflation remaining about the Fed target and averaging about 2.3% a year for the next decade.
The US 2s10s curve, seen as an indicator of economic expectations, was at a positive 27.9 basis points, the flattest since 3 June.
Market expectations of rate hike at the October meeting were roughly 50% from 54% prior to the hike, according to CME FedWatch.
Eurozone borrowing costs fell on Wednesday due to the drop in oil prices.
Germany's 10-year bond yield was down -3 bps at 3.50% after reaching 3.57% on Tuesday for its highest since June 2009.
Germany’s 2-year Schatz yield, which reflects expectations for the ECB rate outlook, was down -3 bps to 3.203% after reaching 3.3123% on Monday for their highest since September 2023.
Earlier in the day, the ECB had said that euro-area pay increases will likely pick up in 2027, according to the ECB wage tracker. It predicts salaries will rise by an annual 2.7% in the first quarter of next year and 2.8% in the second. This is still significantly below 2024’s 5.2% peak.
After last week’s 25 bps rate rise, traders see the ECB's deposit rate at about 2.85% by December, up from the current 2.50%. Market participants expect the rate to reach roughly 3.4% by November 2027, fully pricing a third increase and pointing to a roughly 50% chance of a fourth move.
France’s 10-year government bond yields fell -3 bps to 4.468% after hitting 4.5531% on Tuesday, the highest level since September 2008. The spread between French and German 10-yields was at 96 bps after reaching 98.15 bps on Tuesday, the highest since July 2012.
Italy’s 10-year government bond yields declined -4 bps to 4.38%.
Note: As of 4 pm EDT 16 September 2026
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
This article is provided to you for informational purposes only and should not be regarded as an offer or solicitation of an offer to buy or sell any investments or related services that may be referenced here. Trading financial instruments involves significant risk of loss and may not be suitable for all investors. Past performance is not a reliable indicator of future performance.
 Back to all insights





Created by professionals. For professionals.
