

The Old Lady keeps her options open
Chart of the Day
Index Performance
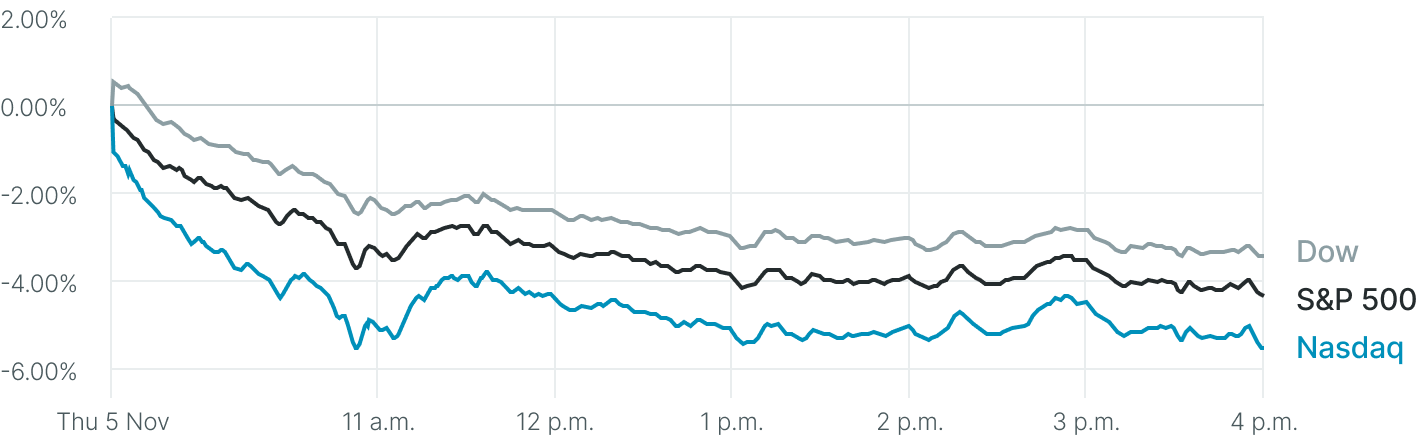
Source: FactSet. As of November 5, 3:59 PM ET
The Old lady of Threadneedle street raises rates
In an 8 - 1 vote, the BoE raised the Bank Rate by 25 bps to 4% due to stronger activity and inflationary pressures feeding through the economy. BoE Governor Andrew Bailey argued that further tightening could be justified unless incoming evidence tempers inflation risks, while Chief Economist Huw Pill also supported additional increases. MPC members Sarah Breeden, Dave Ramsden and Clare Lombardelli highlighted downside risks to inflation. Guidance preserved flexibility, with subsequent decisions dependent on incoming evidence.
The Bank projects inflation peaking at 4.9% in Q2 of 2027. It is expected to return to target only in late 2028, despite Budget measures expected to subtract 0.25 percentage points in the second quarter of 2027. Growth forecasts rose to 1.6% for 2026 and 1.3% for 2027, from 1.1% for both years, but fell to 1.2% for 2028 from 1.7%.
Equities
The Nasdaq Composite entered into correction territory on Thursday due to prospective opposition to data centre development complicating the timeframe for the AI buildout, despite no immediate change in federal policy.
Although slower construction could improve capital discipline for the largest spenders, it undermines growth assumptions for their suppliers. The US election has proven to be a catalyst for investors to question whether growth and unbridled CapEx has peaked.
The sharp Treasury rally and bull steepening also point towards concern about growth if AI investment slows.
- S&P 500 7,353.73 -4.36%
- Nasdaq Composite 24,315.00 -5.52%
- Dow Jones Industrial 51,523.06 -3.44%
- DAX 26,325.01 -0.43%
- CAC 40 8,205.37 +0.34%
- FTSE 100 10,782.66 -0.43%
Currencies
The dollar index was broadly unchanged on Thursday. Sterling edged higher after the BoE raised interest rates for the first time in more than three years and warned that at least one further increase was likely if the US - Iran conflict persisted.
The yen also strengthened against the dollar as minutes from the BoJ’s September meeting reinforced expectations of further interest rate increases.
- DXY 101.59 +0.06%
- EUR/USD $1.1218 -0.08%
- GBP/USD $1.3411 +0.04%
- USD/JPY ¥157.66 -0.45%
- Bitcoin 75,752.79 -5.52%
- Ethereum 2,227.17 -7.86%
Fixed Income
US Treasuries attracted safe-haven demand on Thursday. During the session, the 10-year Treasury yield fell to its lowest level since 9 September, the 30-year yield to its lowest level since 8 September and the 2-year to its lowest level since 10 September.
Eurozone government bond yields also declined with France’s 10-year OAT yield touching a roughly one-month low early in the session. The spread between 10-year OAT and Bund yields was 152.1 bps. Eurozone inflation accelerated to 4.0% in October from 3.8% in September. Money markets are pricing in approximately a 63% probability of another ECB deposit rate increase in December.
- US Treasury 10-year -5.0 bps 4.839%
- German Bund 10-year -3.4 bps 3.261%
- UK Gilt 10-year +0.5 bps 5.140%
- France OAT 10-year -3.8 bps 4.782%
- Italy 10-year -1.8 bps 4.315%
Commodities
Gold prices reached a two-week high, touching $4,146.63 per ounce intraday. Poland’s central bank reached its previously announced gold reserve target of 700 metric tons while leaving open the possibility of further purchases.
Crude oil benchmarks closed higher as markets continued to assess the implications of Tuesday’s US midterm elections for the war in Iran. Additional House and Senate Democrats joined those who had called on Wednesday for an end to the conflict. The New York Times reported that Iran was reviewing a proposal from mediators about its nuclear program.
- Spot Gold $4,086.89/oz +0.62%
- Spot Silver $52.01/oz -0.45%
- WTI crude $91.20 +3.59%
- Brent Crude $99.19/oz +4.15%
Corporate Earnings Today
Companies reporting on Friday, 6th November:
Key data to move markets today
Attention turns to US NFP report
 German Industrial Production, Eurozone Retail Sales and a speech by ECB Chief Economist Philip Lane
 Average Hourly Earnings, Labour Force Participation, Nonfarm Payrolls, U6 Underemployment, Unemployment Rate, Michigan Consumer Sentiment and Expectations Indices, UoM 1- and 5-year Consumer Inflation Expectations and speeches by New York Fed President John Williams and Fed Governor Michelle Bowman
 A speech by BoJ Governor Kazuo Ueda
FEATURED TODAY
Equity Monthly Review
When the biggest stocks stop leading, where does the market’s strength come from?
In October, the S&P 500 fell 0.93%, but its equal-weight version rose 4.90%, outpacing it by 583 basis points.
Read EXANTE’s Equity Monthly Review by Multi-Asset Strategist Horacio Coutino for the full picture.
Renée Friedman, PhD
Editor-in-Chief, EXANTE
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
Tento článek je poskytován pouze pro informační účely a neměl by být považován za nabídku nebo výzvu k nákupu nebo prodeji jakýchkoli investic nebo souvisejících služeb, jejichž odkazy se v něm můžou vyskytovat. Obchodování s finančními nástroji je spojeno se značným rizikem ztráty a nemusí být vhodné pro všechny investory. Dřívější produktivita není spolehlivým ukazatelem budoucí produktivity.
 Zpět na všechny přehledy


Přihlásit se k odběru přehledů trhu
Přihlásit se k odběru
přehledů
trhu
Předplaťte si nyní Předplaťte si nyní

Založeno profesionály. Pro profesionály.
