

Japan’s normalisation trade
Stock-index performance
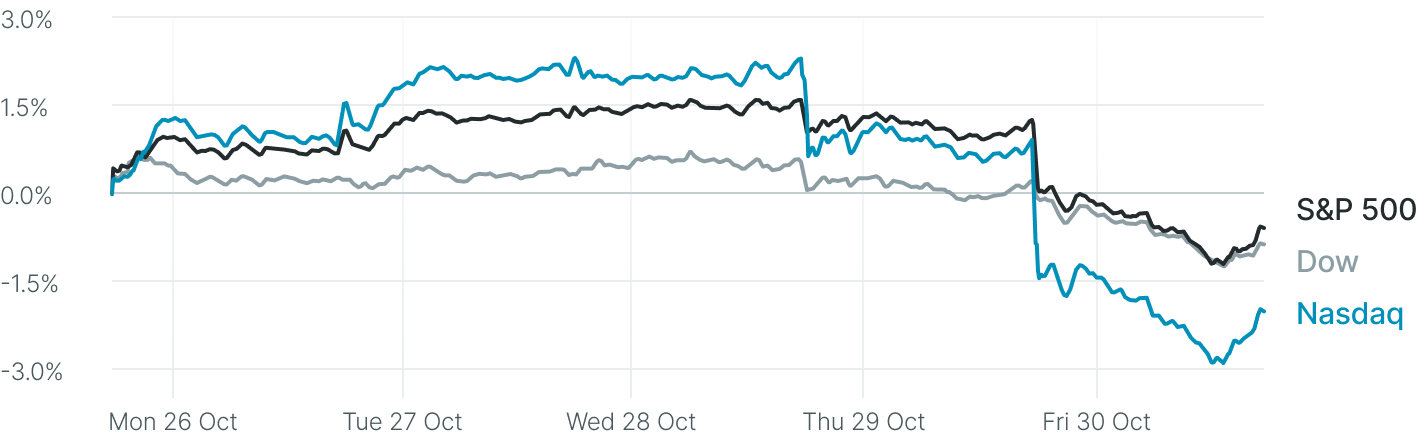
Source: FactSet As of Oct. 30, 4 p.m. ET
The BoJ holds
The BoJ held rates at 1.25%, with the Outlook for core inflation in 2027 at 2.6%, suggesting further tightening, even as expensive energy squeezes real incomes.
This is a rotation story for Japenese assets. Faster tightening could support the yen, temper exporters’ translation gains and ease importers’ cost pressures, although US rates and Japan’s fiscal credibility complicate any straightforward currency rebound. JGBs face renewed repricing risk. Accelerated ETF disposals add a separate equity headwind. Annual sales of roughly ¥2.46 trillion at market value from January remain modest against turnover, but could amplify weakness when buyers retreat. Governance reform and corporate buybacks still provide support; the BoJ’s withdrawal does not undermine the case for Japanese equities.
Equities
The tech selloff deepened with Intel plunging 28.58%. All three major US indices fell. Last Thursday’s and Friday’s sell-off left the Nasdaq 7.80% below its record high, making October its worst month since March 2025.
AI concerns were compounded following a major cyberattack on Binance after hackers stole an estimated $6.3 billion from the exchange.
- S&P 500 7,580.07 -1.82%
- Nasdaq Composite 25,437.00 -2.86%
- Dow Jones Industrial 51,770.31 -1.09%
- DAX 25,818.21 -0.85%
- CAC 40 7,969.42 -0.01%
- FTSE 100 10,729.78 +0.07%
Currencies
The yen ended the week higher after the BoJ kept rates at 1.25%, and raised its inflation outlook. The US dollar index rose 0.49% in October after gaining 2.07% in September. The euro fell 1.51% against the US dollar in October.
- DXY 101.96 +0.07%
- EUR/USD $1.1158 -0.18%
- GBP/USD $1.3391 +0.12%
- USD/JPY ¥157.53 -0.10%
- Bitcoin 76,809.49 -2.58%
- Ethereum 2,236.67 -1.02%
Fixed Income
US Treasuries rallied on Friday with the benchmark10-year yield down 35.7 bps in October, its largest monthly decline in nearly three years. The CME FedWatch Tool puts the odds of a December US rate hike at 72.0%.
French government yields climbed on shrinking Q3 GDP. The French-German yield spread widened 38.5 bps in October to 163.0 bps, its highest since the 2011 eurozone crisis. Money markets price in an 83.0% chance of a 25 bps increase in the ECB rate in December.
- US Treasury 10-year -0.4 bps 4.934%
- German Bund 10-year -3.0 bps 3.342%
- UK Gilt 10-year -1.1 bps 5.290%
- France OAT 10-year +6.1 bps 4.972%
- Italy 10-year +1.2 bps 4.487%
Commodities
Gold hit a one-year low on Friday as investors scrambled to cover equity margin calls amid a liquidity squeez. Silver fell sharply into technically oversold territory. Houthi attacks from Yemen against Saudi Arabia, increased Iranian attacks on tankers in the Strait of Hormuz, and the prospect of renewed US - Israel strikes on Iran remained key drivers of crude and refined product prices last week.
- Spot Gold $3,875.02/oz -3.62%
- Spot Silver $49.10/oz -6.16%
- WTI crude $102.95 +0.09%
- Brent crude $117.55 +3.04%
Corporate Earnings Today
Companies reporting on Monday, 2nd November: Apple, Diamondback Energy, Fox, Loews, Lottomatica Group, Marriott International, ON Semiconductor, Palantir Technologies, Progressive, SBA Communications, Ryanair Holdings, Vertex Pharmaceuticals
Key data to move markets today
Attention turns to global PMIs for signs of inflation accelerating ahead of tomorrow’s US Midterm Elections
 German Retail Sales, Eurozone, Spanish, Italian, French and German HCOB Manufacturing PMIs and a speech by ECB Vice President Boris Vujčić
 S&P Global Manufacturing PMI
 S&P Global Manufacturing PMI, ISM Manufacturing PMI, Prices Paid and Employment and New Orders Indices, Fed’s Loan Officer Survey and a speech by Chicago Fed President Austan Goolsbee
 Banks will be closed due to Culture Day bank holiday
FEATURED TODAY
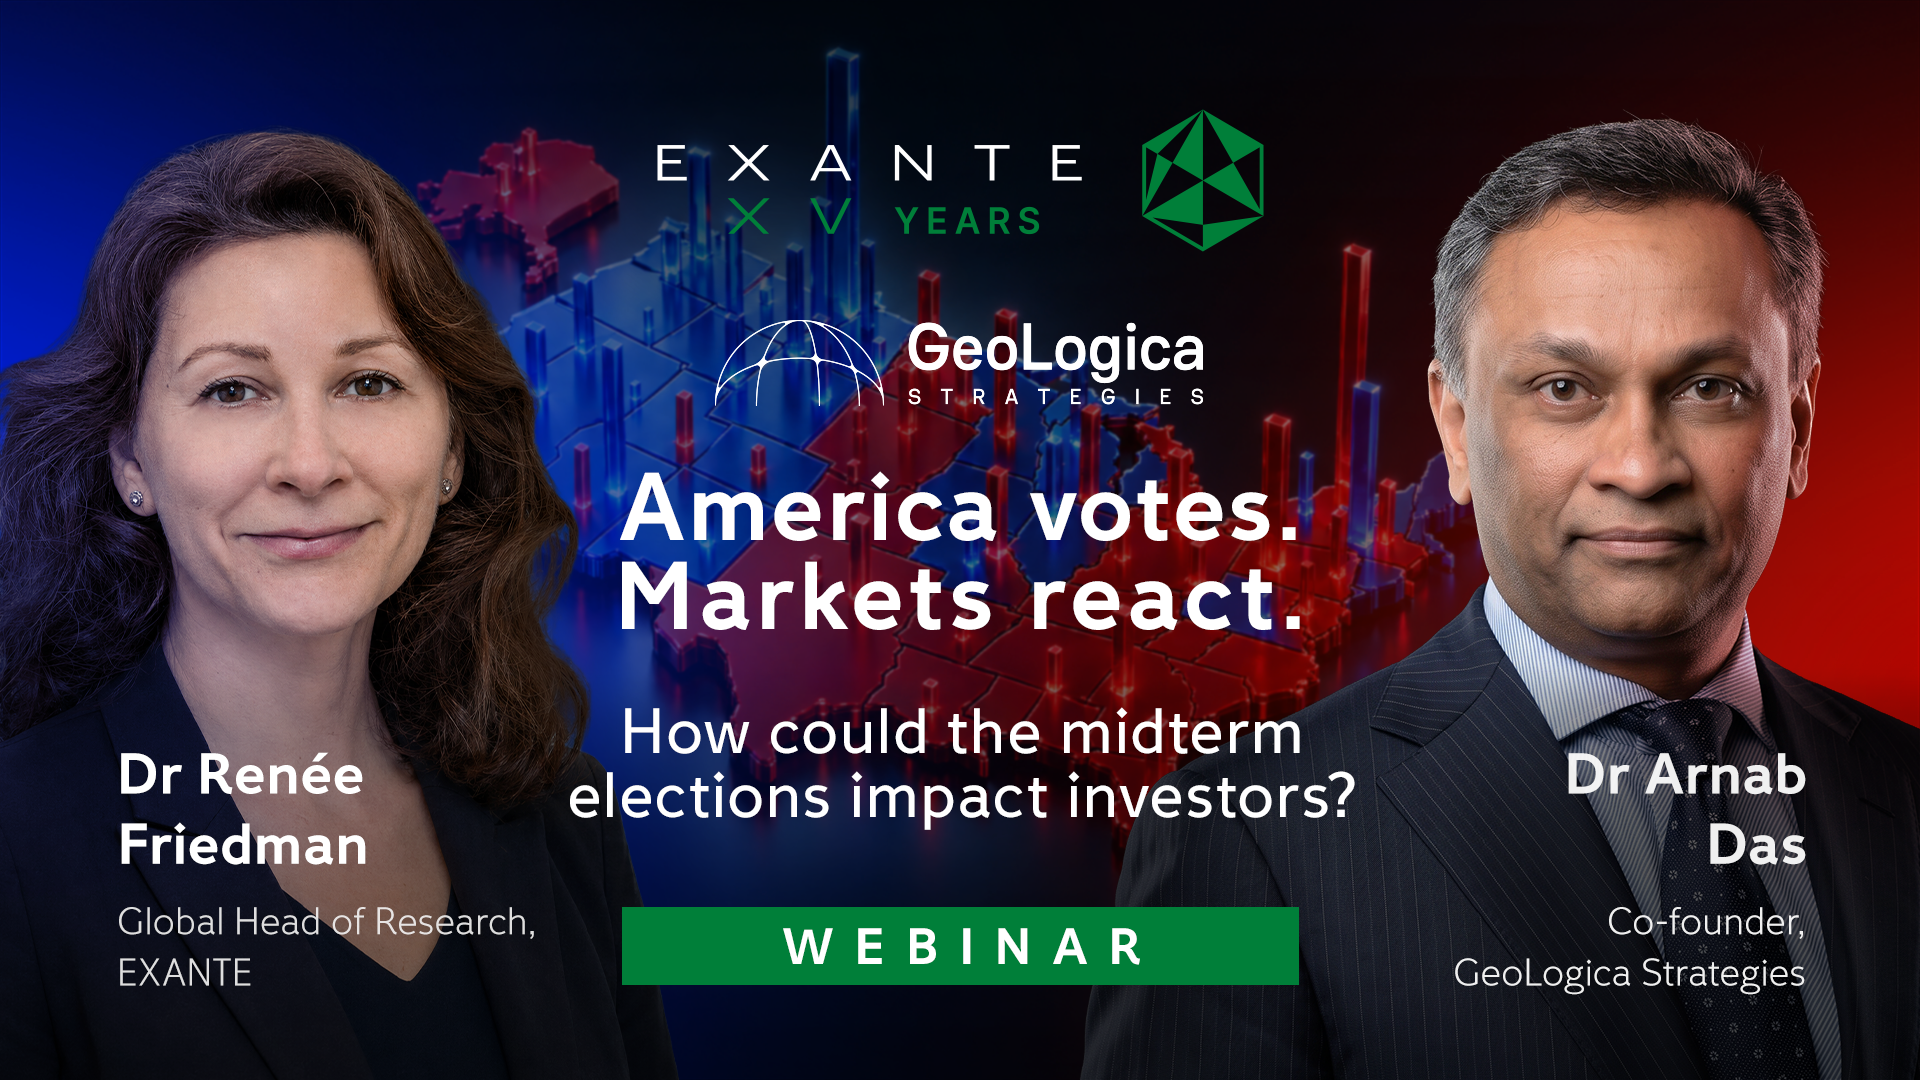
America votes. Markets react.
What signals should investors be watching for in the US midterms? Watch our special US midterms preview webinar with Renée Friedman, EXANTE Global Head of Research, and Arnab Das, Co-founder of GeoLogica Strategies.
They covered what matters most to US voters and financial markets, how global markets and traders may react and which markets could be the biggest winners or losers.
Renée Friedman, PhD
Editor-in-Chief, EXANTE
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
Tento článek je poskytován pouze pro informační účely a neměl by být považován za nabídku nebo výzvu k nákupu nebo prodeji jakýchkoli investic nebo souvisejících služeb, jejichž odkazy se v něm můžou vyskytovat. Obchodování s finančními nástroji je spojeno se značným rizikem ztráty a nemusí být vhodné pro všechny investory. Dřívější produktivita není spolehlivým ukazatelem budoucí produktivity.


Přihlásit se k odběru přehledů trhu
Přihlásit se k odběru
přehledů
trhu
Předplaťte si nyní Předplaťte si nyní

Založeno profesionály. Pro profesionály.
