
What will cause rates to take flight?

 S&P 500 +0.28% to 7,743.98 US 10-year yield +1.8 basis points to 5.021% Spot gold +0.18% to $4,066.96 an ounce DXY -0.21% to 102.14
What to look out for today
Companies reporting on Thursday, 29th October: Amazon, Bristol-Myers Squibb, Caterpillar, Coinbase Global, Eli Lilly & Co., Fiverr International, Gilead Sciences, Intel, Mastercard, Merck & Co., Mondelez International, Pinterest, Rivian Automotive, Sandisk, Starbucks, Strategy Inc., Takeda Pharmaceuticals, Twilio
Key data to move markets today
EU: Eurozone Business Climate, Consumer Confidence and Economic Sentiment Indicator, ECB Main Refinancing Operations Rate, ECB Monetary Policy Statement, ECB Rate on Deposit Facility, ECB Press Conference and a speech by ECB Executive Board member Piero Cipollone
USA: Initial and Continuing Jobless Claims, GDP, Core Personal Consumption Expenditures Price Index, Personal Consumption Expenditures Price Index, Personal Consumption Expenditures Prices, Core Personal Consumption Expenditures, Personal Income and Personal Spending
JAPAN: Tokyo Consumer Price Index, Unemployment Rate, Large Retailer Sales and Retail Trade
Global Macro Updates
The Fed call. The Fed’s hold at 3.75% – 4.00% offers markets breathing room, but not an all-clear. Fed Governor Lisa Cook and Cleveland Fed President Beth Hammack preferred another hike, while the statement upgraded growth to ‘strong’ and made further information the justification for waiting.
For Treasuries, the key distinction is between policy-rate risk and term-premium risk. The front end can rally on greater patience while longer maturities remain vulnerable to inflation uncertainty and heavy financing requirements. September’s minutes identified AI-related borrowing among the forces lifting term premia. The Financial Times also flagged funding-market pressures. Duration is not a single trade.
Equities and credit face a related asymmetry. Stronger activity supports earnings, but persistent inflation limits valuation relief. Renewed AI financing underscores the need to distinguish beneficiaries of investment from the issuers funding it. Investors need to consider FCF, refinancing schedules and interest coverage rather than mistake elevated yields for adequate compensation.
Fed minutes also documented dollar depreciation despite rising US yields as foreign rate expectations increased faster. The dollar’s immediate decline need not persist if US tightening expectations strengthen against those abroad. However, higher Treasury yields alone may not be sufficient to support the dollar. The continued strength of the US economy and of the AI trade may be more supportive.
US Stock Indices
Dow Jones Industrial Average +0.19%
Nasdaq 100 +0.55%
S&P 500 +0.28%, with 8 of the 11 sectors of the S&P 500 up
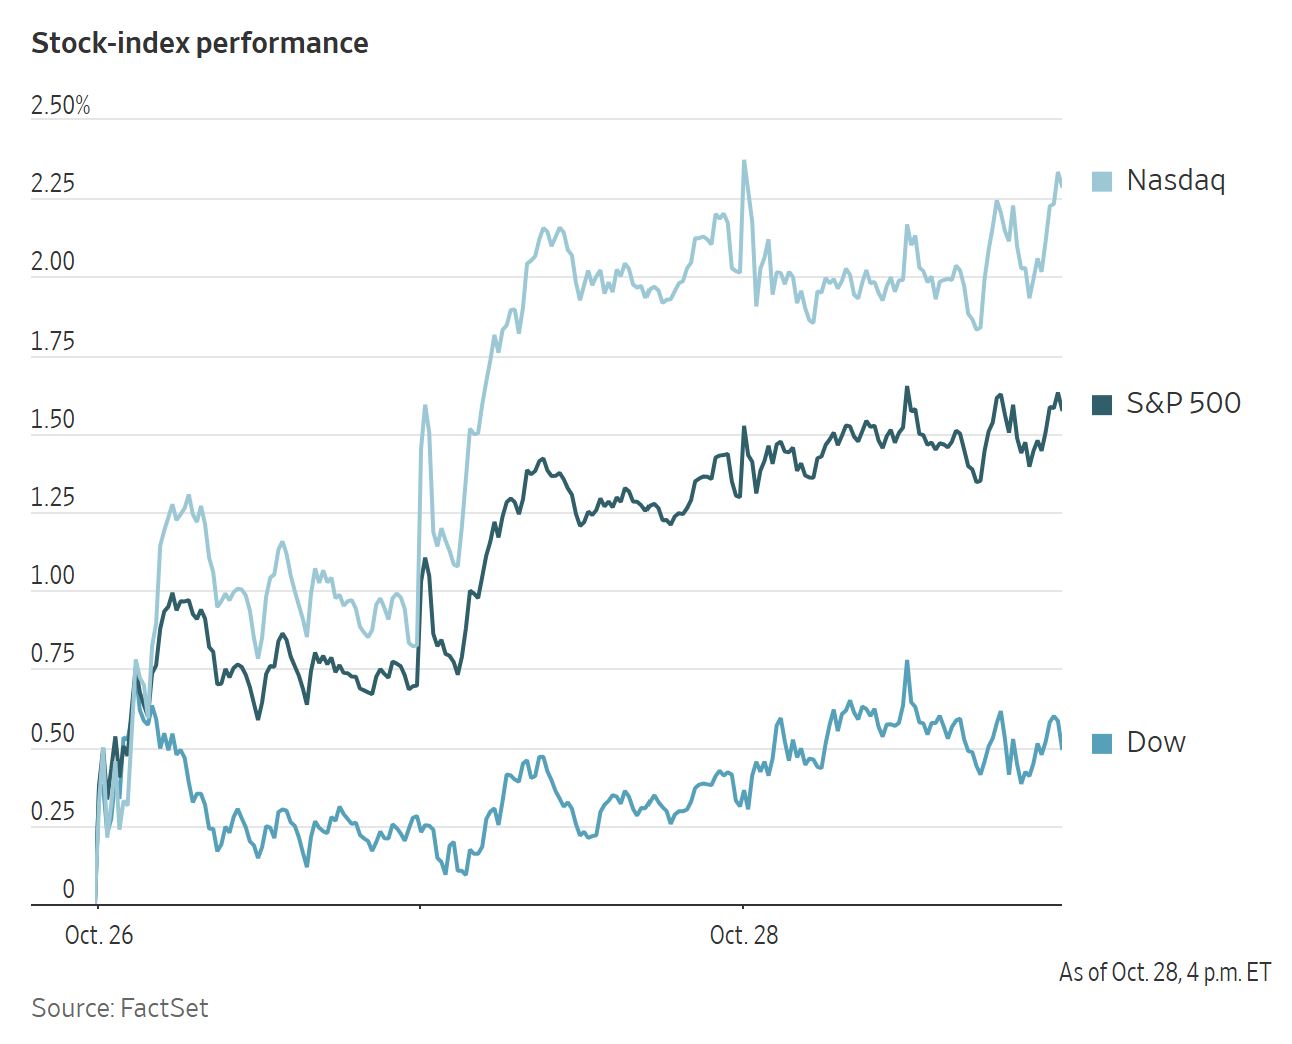
US stocks and longer-term bond yields edged higher after the Fed left rates unchanged, as expected. Investors viewed Chair Kevin Warsh’s remarks as slightly dovish.
Warsh’s tone supported equities, with the Dow Jones Industrial Average gaining +0.19%, or 97.53 points, while the S&P 500 and Nasdaq Composite rose +0.28% and +0.27%, respectively.
Wednesday’s advance ended the S&P 500’s six-session losing streak on Fed decision days, its second-longest such run since 1994.
In corporate news, the results of Alphabet and Microsoft’s earnings reports offer fresh insight into returns on AI infrastructure investment and could renew concerns over spending.
Microsoft and Google supply computing power to OpenAI and Anthropic, making cloud revenue a direct gauge of their earnings from the AI boom.
Alphabet shares fell more than -10% in after-hours trading as revenue missed analyst forecasts, while Microsoft reported revenue exceeding expectations. Its shares rose in after-hours trading.
Azure helped drive Microsoft’s strong quarter, with the division housing the cloud business generating $76.8 billion in revenue.
Alphabet’s Google advertising revenue missed analyst forecasts, while cloud revenue exceeded expectations.
GE Vernova said it will buy high-voltage grid equipment manufacturer Trench Group for $9 billion to expand its electrification business and capitalise on surging investment in power grids.
Nelson Peltz’s Trian Fund Management proposed buying Wendy’s for about $1.4 billion, arguing that private ownership would better support a multiyear turnaround. The $7.35-per-share cash offer for all outstanding shares represents a +20% premium to Tuesday’s close and remains subject to negotiation. Trian plans to engage with management and the board, while an independent Wendy’s board committee will assess the proposal.
Corporate Earnings Reports
Posted on Wednesday, 28 October from The Pulse, our real-time AI-driven news tool. Available exclusively on the EXANTE Web Platform
GE Vernova reported third-quarter 2026 revenue of $12.64bn vs $11.99bn expected, up +27% y/y, with EPS of $4.81. Orders surged +96% organically to $29.3bn, lifting total backlog to $197bn, propelled by Electrification revenue rising +51% y/y to $3.9bn and Power revenue climbing +25% y/y to $6.1bn. For full-year 2026, the firm raised revenue guidance to between $46.5bn and $47.5bn vs $46.24bn consensus, whilst increasing adjusted EBITDA margin guidance to 13.5% to 14.5%. GE Vernova also announced a $9.0bn acquisition of Trench Group and expanded its share buyback authorisation to $20bn. The Chief Executive Officer stated that strong electricity infrastructure demand supported results and backlog is expected to surpass $200bn in the fourth quarter.
Boston Scientific reported Q3 2026 net sales of $5.14bn vs $5.05bn expected, with adjusted EPS of $0.73 vs $0.72 expected, down -3% y/y. MedSurg revenue rose +0.6% y/y to $1.7bn, Cardiovascular increased +1.9% y/y to $3.4bn, and Neuromodulation grew +13.1% y/y to $331mn. Boston Scientific lowered its full-year guidance due to disruptions from a cyberattack, forecasting FY26 adjusted EPS of $3.16 to $3.18 vs $3.23 expected and Q4 adjusted EPS of $0.77 to $0.79 vs $0.84 expected. The company also secured FDA 510(k) clearances for StoneSmart Solutions and expanded sizing for SEISMIQ. The chief executive stated that the team responded with urgency to restore operations post-incident and expressed confidence in their long-term innovation pipeline.
Vertiv reported Q3 2026 revenue of $4.3bn vs $3.76bn expected, representing an increase of +61% y/y, and adjusted EPS of $2.21 vs $1.83 expected, up +78% y/y. Organic net sales grew +55% y/y, while adjusted free cash flow increased +50% y/y to $652mn vs $373mn expected. For FY26, the company raised revenue guidance to $14.45bn to $14.85bn vs $14.02bn expected and adjusted EPS guidance to $7.10 to $7.20 vs $6.74 expected. Chief Executive Giordano Albertazzi stated that the company is in the middle of an accelerating infrastructure buildout.
Alphabet reported third-quarter 2026 revenue of $127.58bn, up +24.7% y/y but missing consensus of $127.93bn, and earnings per share of $2.12 vs $3.01 expected. Results were weighed down by an $8.2bn unrealised loss on its SpaceX investment and slowing search advertising growth, while Google Cloud revenue rose +102.6% y/y to $30.71bn vs $29.10bn expected. Free cash flow dropped to negative -$9.1bn as technical infrastructure capital expenditure reached $51.36bn. Alphabet maintained its full-year capital expenditure guidance of $195bn to $205bn and noted capital spending will increase significantly in 2027. Chief Executive Officer Sundar Pichai stated that the company achieved a half-trillion dollar annual revenue run rate supported by robust momentum in AI and cloud infrastructure.
Microsoft reported Q1 FY27 revenue of $92.28bn, up +18.8% y/y vs $90.63bn expected, and adjusted EPS of $4.89 vs $4.73 expected. Cloud revenue rose +30.0% y/y to $63.9bn, driven by Azure revenue climbing +48.0% y/y, whilst capital expenditure reached $39.37bn vs $45.93bn expected. For Q2, management guided revenue to between $96.0bn and $97.1bn alongside constant-currency Azure growth projected up +49.0% to +50.0%, with quarterly capex expected to exceed $50bn. Operationally, the firm offered voluntary exit packages to approximately 60,000 employees to manage operational overheads whilst scaling artificial intelligence infrastructure. Chief Executive Officer Satya Nadella stated that the company is translating its innovation into growing enterprise adoption and real-world impact across every industry.
ServiceNow reported Q3 2026 revenue of $4.1bn vs $4.09bn expected, whilst adjusted EPS missed consensus at $1.00 vs $1.02. Current remaining performance obligations reached $13.65bn vs $13.56bn expected, up +20.5% y/y. For full-year 2026, ServiceNow raised its subscription revenue guidance to between $15.78bn and $15.79bn, lifted its free cash flow margin target to 36%, and increased its artificial intelligence annual contract value target to over $1.7bn. For Q4, current remaining performance obligations growth is projected to slow to +18.5% y/y. In commercial developments, the group announced artificial intelligence partnerships with OpenAI, Google Cloud, and Hewlett Packard Enterprise. The chief executive stated that the company is capturing substantial opportunities through a capital-efficient model at the forefront of the agentic enterprise.
KLA reported Q1 fiscal 2027 revenue of $4.14bn vs $4.04bn estimated, up +29% y/y, and adjusted EPS of $1.22 vs $1.18 estimated, up +39% y/y. Semiconductor Process Control revenue reached $3.75bn, PCB and Component Inspection generated $242.2mn, and Specialty Semiconductor Process delivered $139.5mn. Capital returns totalled $1.24bn, comprising $935.8mn in share repurchases and $305.1mn in dividends. For Q2, KLA guided revenue to $4.7bn plus or minus $200mn vs $4.54bn expected and adjusted EPS to $1.44 plus or minus $0.11 vs $1.38 expected, with non-GAAP gross margin targeted at 62.5% plus or minus 1.0%. The Chief Executive Officer stated that the quarter beat guidance midpoints across all key metrics and highlighted that process control remains critical to artificial intelligence ecosystem expansion.
Ford reported third-quarter adjusted EPS of $0.49 vs $0.41 expected, alongside revenue of $49.5bn vs $48.9bn expected, which fell -2.0% y/y. Adjusted EBIT reached $2.66bn vs $2.38bn expected. By division, Ford Blue revenue dropped -3.0% y/y to $27.1bn, whilst Model e revenue fell -31.0% y/y to $1.2bn. For the full year, the carmaker raised the lower end of its adjusted EBIT guidance range to between $10.5bn and $11bn, while maintaining its adjusted free cash flow outlook between $6bn and $7bn. Separately, the United States and Canada are negotiating potential relief on automotive tariffs. Chief Executive Jim Farley stated that ongoing cost reductions and record software revenue show the firm is expanding beyond standard vehicle sales.
Chipotle reported its Q3 2026 financial results after market close, delivering revenue of $3.3bn, up +9.6% y/y vs expectations of $3.28bn to $3.29bn, while adjusted EPS missed forecasts at $0.27 vs $0.29 expected. Net income fell -11.1% y/y to $339.9mn, and restaurant-level margins reached 23.3%. Comparable restaurant sales rose +2.1% vs consensus estimates of +1.4% to +1.5%, supported by transactions up +0.8% and average check growth of +1.3%. For full-year 2026, Chipotle guided comparable sales growth in the low-single-digit range and planned 350 to 370 new restaurant openings. Chief Executive Officer Scott Boatwright stated that three consecutive quarters of positive comparable transaction growth demonstrated that the firm's growth strategy is working.
T-Mobile US reported Q3 2026 revenue of $23.58bn vs $23.14bn expected, which rose +7.4% y/y, and EPS of $3.22 vs $2.91 expected, up +34% y/y. Net income rose +27% y/y to $3.5bn, and core adjusted EBITDA increased +11% y/y to $9.62bn vs $9.42bn expected, driven by 274,000 postpaid net account additions. For full-year 2026, guidance for core adjusted EBITDA was raised to between $37.35bn and $37.45bn, and adjusted free cash flow to between $18.7bn and $18.8bn. In corporate developments, Deutsche Telekom reportedly paused plans to merge with T-Mobile US. Leadership stated that the quarter delivered durable, profitable growth across core wireless and broadband services.
European Stock Indices
CAC 40 -0.00%
DAX +0.44%
FTSE 100 +0.07%
Commodities
Gold spot +0.18% to $4,066.96 an ounce
Silver spot -0.85% to $53.95 an ounce
West Texas Intermediate +1.74% to $101.94 a barrel
Brent crude -0.08% to $114.13 a barrel
Gold prices edged higher on Wednesday as investors assessed Fed Chair Kevin Warsh’s comments after the FOMC, as widely expected, left the Fed funds target range unchanged.
Spot gold rose +0.18% to $4,066.96 per ounce.
China’s net gold imports via Hong Kong increased by more than +28% in September from August, reaching a five-month high as restocking ahead of the Golden Week holiday and investor demand supported purchases.
Spot silver, meanwhile, fell -0.85% to $53.95 per ounce.
Oil prices ended Wednesday’s session mixed as continued fighting in Yemen, an attack on a Saudi refinery and concerns over potential US strikes on Iran after next week’s US midterm elections renewed fears of further disruptions to Middle Eastern energy supplies.
Brent futures fell 9 cents, or -0.08%, to settle at $114.13 per barrel. WTI crude gained $1.74, or +1.74%, to close at $101.94 per barrel.
Yemeni government forces said the Iran-aligned Houthis attacked Aden airport on Wednesday after warning people to evacuate the facility.
Overnight media reports indicated that the US had advised several Gulf Arab nations to prepare for a brief, but intense military campaign after the elections.
Diplomatic efforts continued alongside these concerns. Sources familiar with the matter told Reuters that Qatari mediators presented Iran with a new draft agreement on Sunday. Axios reported yesterday afternoon that Arab mediators were pressing Tehran to make nuclear concessions amid the prospect of large-scale strikes after the midterm elections.
An Axios source said Iran could receive waivers to sell oil and gain access to some frozen funds for food and other humanitarian purchases if it allowed UN inspectors to visit its nuclear sites.
Crude prices subsequently moved lower following reports that Vice President Vance had contacted Iranian security chief Mohsen Rezaei to seek a resumption of peace negotiations before potential US military strikes after the elections.
On inventories, the DOE’s Weekly Petroleum Status Report showed a 1.890 million barrel decline in crude stocks, the fourth consecutive draw. This brought the cumulative reduction over that period to 16.690 million barrels.
Total gasoline inventories increased by 3.870 million barrels as demand weakened, although stocks in PADD 2 fell to a record low of 41.0 million barrels.
Distillate inventories declined by 1.460 million barrels, supported by stronger demand and higher net exports.
China also issued a fourth batch of export quotas for gasoline, diesel and jet fuel. The rare additional allocation brought the 2026 total into line with 2025 despite restrictions earlier in the year.
Attention now turns to Sunday’s OPEC+ meeting, where producers are expected to leave December output targets unchanged, according to people familiar with the matter cited by Reuters.
Most of the seven core OPEC+ members, Saudi Arabia, Russia, Iraq, Kuwait, Algeria, Kazakhstan and Oman, are producing below their targets.
Separately, traders said Russian crude exports from Baltic and Black Sea ports could decline next month as domestic refiners increase diesel production following this month’s agreement with Washington.
Note: As of 4 pm EDT 28 October 2026
Currencies
EUR +0.27% to $1.1152
GBP +0.17% to $1.3325
Bitcoin +0.71% to $81,273.58
Ethereum +0.74% to $2,359.06
The US dollar weakened against major currencies on Wednesday after the Fed, as expected, left rates unchanged. The dollar index declined -0.21% to 102.14.
The initial reaction to the decision was muted, but the dollar lost ground during Fed Chair Kevin Warsh’s press briefing. The euro gained +0.27% to $1.1152, while the dollar fell -0.08% against the yen to ¥157.82.
Sterling rose +0.17% against the dollar to $1.3325, but fell approximately -0.08% against the euro.
The ECB and BoJ are scheduled to announce policy decisions today and on Friday, respectively, with both expected to leave rates unchanged.
Fixed Income
US 10-year Treasury +1.8 basis points to 5.021%
German 10-year Bund +1.1 basis points to 3.386%
UK 10-year Gilt -2.5 basis points to 5.329%
Longer-dated US Treasury yields extended their early gains on Wednesday afternoon as the Fed expressed confidence in the economy while leaving rates unchanged, reinforcing expectations of a December hike.
The two-year Treasury yield rose +3.9 bps to 4.745%.
The US 2s10s yield spread narrowed by 2.1 bps to 27.6 bps from 29.7 bps on Tuesday.
Rate futures priced in a 78.4% probability of a 25 bps hike at the Fed’s December meeting, up from 76.1% a week earlier, according to CME’s FedWatch tool.
The 10-year Treasury yield rose +1.8 bps to 5.021%, reaching its highest level since last Thursday. The 30-year yield declined -3.3 bps to 5.314%, although it also touched its highest level since Thursday during the session.
Eurozone government bond yields rose across countries and maturities on Wednesday.
Germany’s 10-year Bund yield increased +1.1 bps to 3.386%.
France’s 10-year OAT yield rose +2.0 bps to 4.942%, remaining just below the 5.0% threshold breached last week. Its spread over 10-year Bunds stood at 155.6 bps.
Shorter-dated yields, which are more sensitive to policy expectations, also increased. Germany’s two-year Schatz yield rose +4.4 bps to 3.138%.
Italy’s 10-year BTP yield gained +3.1 bps to 4.522%.
The ECB is scheduled to announce its next rate decision today and is expected to leave rates unchanged after two hikes earlier this year.
Money markets are not fully pricing in another ECB hike until February 2027, with two hikes fully priced in by April.
Note: As of 4 pm EDT 28 October 2026
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
Tento článek je poskytován pouze pro informační účely a neměl by být považován za nabídku nebo výzvu k nákupu nebo prodeji jakýchkoli investic nebo souvisejících služeb, jejichž odkazy se v něm můžou vyskytovat. Obchodování s finančními nástroji je spojeno se značným rizikem ztráty a nemusí být vhodné pro všechny investory. Dřívější produktivita není spolehlivým ukazatelem budoucí produktivity.
 Zpět na všechny přehledy


Přihlásit se k odběru přehledů trhu
Přihlásit se k odběru
přehledů
trhu
Předplaťte si nyní Předplaťte si nyní

Založeno profesionály. Pro profesionály.
